News Posts matching #Demand

Return to Keyword Browsing

Samsung Electronics Announces Second Quarter 2023 Results

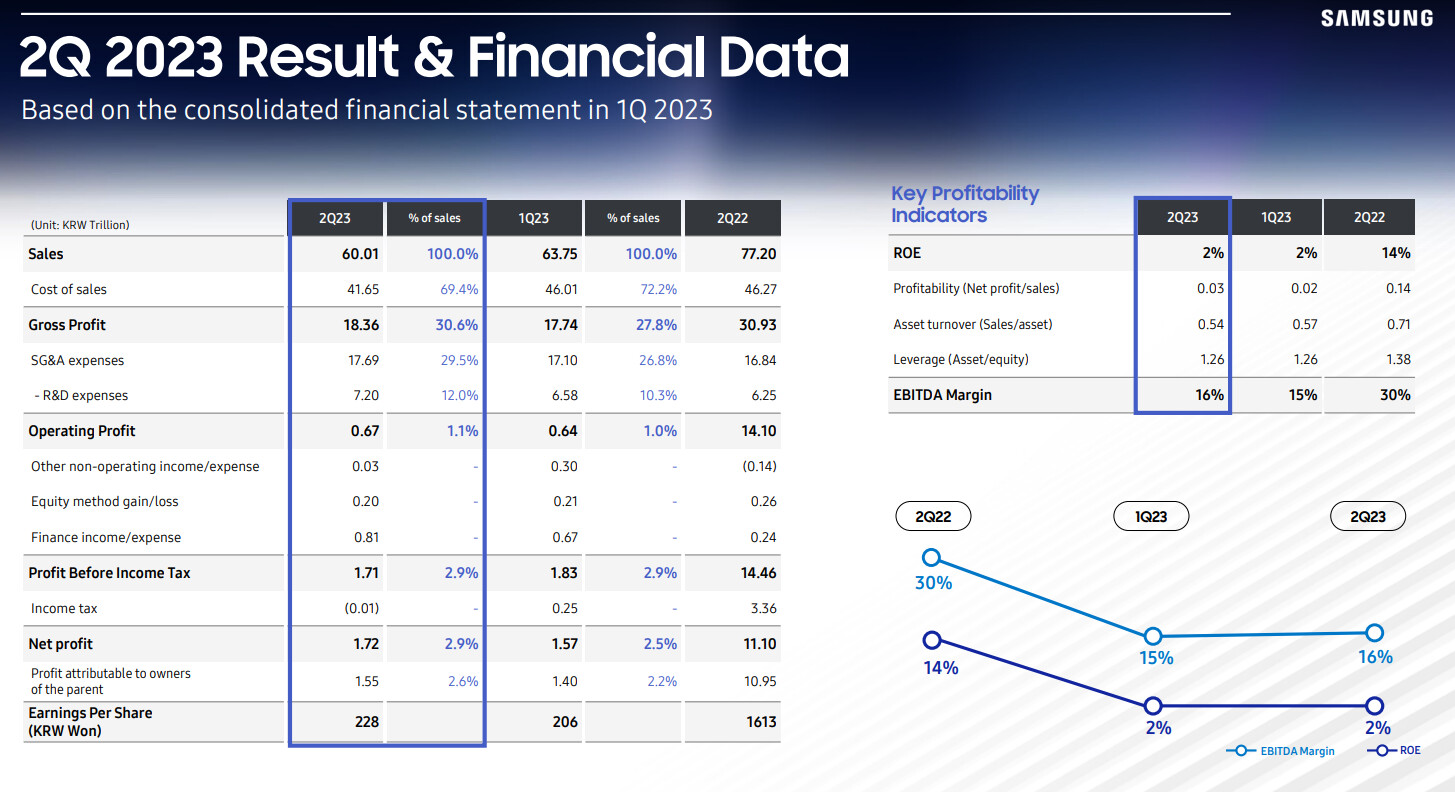
Samsung Electronics today reported financial results for the second quarter ended June 30, 2023. The Company posted KRW 60.01 trillion in consolidated revenue, a 6% decline from the previous quarter, mainly due to a decline in smartphone shipments despite a slight recovery in revenue of the DS (Device Solutions) Division. Operating profit rose sequentially to KRW 0.67 trillion as the DS Division posted a narrower loss, while Samsung Display Corporation (SDC) and the Digital Appliances Business saw improved profitability.

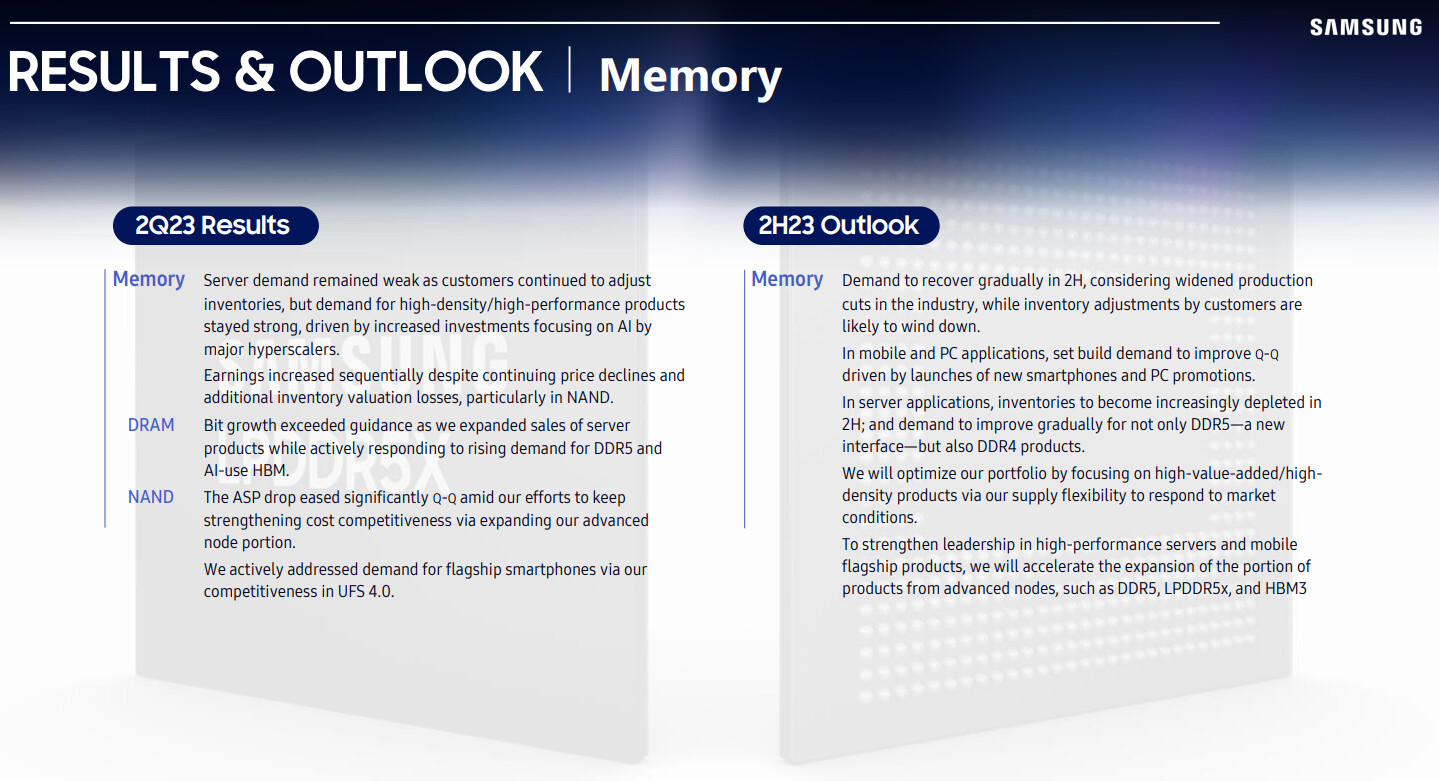
The Memory Business saw results improve from the previous quarter as its focus on High Bandwidth Memory (HBM) and DDR5 products in anticipation of robust demand for AI applications led to higher-than-guided DRAM shipments. System semiconductors posted a decline in profit due to lower utilization rates on weak demand from major applications.

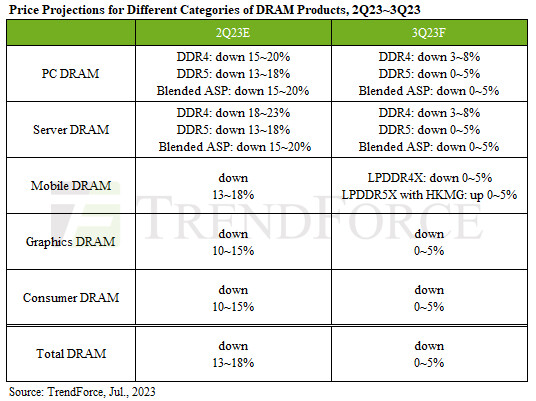
DRAM ASP Decline Narrows to 0~5% for 3Q23 Owing to Production Cuts and Seasonal Demand

TrendForce reports that continued production cuts by DRAM suppliers have led to a gradual quarterly decrease in overall DRAM supply. Seasonal demand, on the other hand, is helping to mitigate inventory pressure on suppliers. TrendForce projects that the third quarter will see the ASP for DRAM converging towards a 0~5% decline. Despite suppliers' concerted efforts, inventory levels persistently remain high, keeping prices low. While production cutbacks may help to curtail quarterly price declines, a tangible recovery in prices may not be seen until 2024.

PC DRAM: The benefits of consolidated production cuts on DDR4 by the top three suppliers are expected to become evident in the third quarter. Furthermore, inventory pressure on suppliers has been partially alleviated due to aggressive purchasing by several OEMs at low prices during 2Q23. Evaluating average price trends for PC DRAM products in 3Q23 reveals that DDR4 will continue to remain in a state of persistent oversupply, leading to an expected quarterly price drop of 3~8%. DDR5 prices—influenced by suppliers' efforts to maintain prices and unmet buyer demand—are projected to see a 0-5% quarterly decline. The overall ASP of PC DRAM is projected to experience a QoQ decline of 0~5% in the third quarter.

Major CSPs Aggressively Constructing AI Servers and Boosting Demand for AI Chips and HBM, Advanced Packaging Capacity Forecasted to Surge 30~40%

TrendForce reports that explosive growth in generative AI applications like chatbots has spurred significant expansion in AI server development in 2023. Major CSPs including Microsoft, Google, AWS, as well as Chinese enterprises like Baidu and ByteDance, have invested heavily in high-end AI servers to continuously train and optimize their AI models. This reliance on high-end AI servers necessitates the use of high-end AI chips, which in turn will not only drive up demand for HBM during 2023~2024, but is also expected to boost growth in advanced packaging capacity by 30~40% in 2024.

TrendForce highlights that to augment the computational efficiency of AI servers and enhance memory transmission bandwidth, leading AI chip makers such as Nvidia, AMD, and Intel have opted to incorporate HBM. Presently, Nvidia's A100 and H100 chips each boast up to 80 GB of HBM2e and HBM3. In its latest integrated CPU and GPU, the Grace Hopper Superchip, Nvidia expanded a single chip's HBM capacity by 20%, hitting a mark of 96 GB. AMD's MI300 also uses HBM3, with the MI300A capacity remaining at 128 GB like its predecessor, while the more advanced MI300X has ramped up to 192 GB, marking a 50% increase. Google is expected to broaden its partnership with Broadcom in late 2023 to produce the AISC AI accelerator chip TPU, which will also incorporate HBM memory, in order to extend AI infrastructure.

Report: DRAM and NAND Flash Prices Expected to Fall Further in 2Q23 Due to Weak Server Shipments and High Inventory Levels

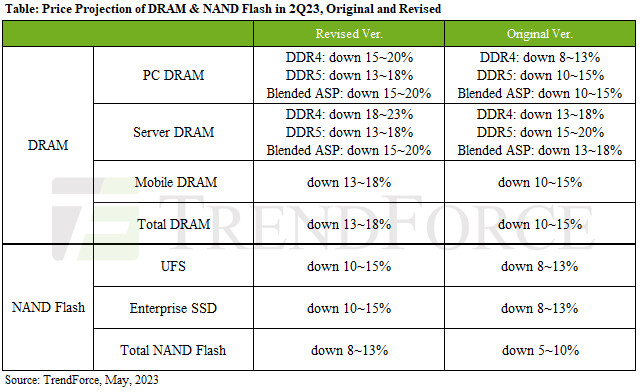
TrendForce's latest research indicates that, as production cuts to DRAM and NAND Flash have not kept pace with weakening demand, the ASP of some products is expected to decline further in 2Q23. DRAM prices are projected to fall 13~18%; NAND Flash is expected to fall between 8~13%.

TrendForce reports that the significant drop in DRAM prices was mostly attributed to high inventory levels of DDR4 and LPDDR5 as PC DRAM, server DRAM, and mobile DRAM collectively account for over 85% of DRAM consumption. Meanwhile, the market share for DDR5 remains relatively low.

AMD Could be Resurrecting Ryzen 3000G APU Series

AMD is reported to be reissuing its old Zen+ (12 nm) tech in order to meet demand for cheaper, lower-end systems in China, according to information released by Board Channels this week. The insider source claims that a new production order has been placed for Ryzen 3000G series APUs (requesting up to 30,000 units) and these processors are likely to be sold as part of hardware bundles with (similar vintage) low-end AM4-based motherboards - for example the B450 and A320 series, these older boards are still popular budget choices in China and readily available. The leak does not mention whether AMD is choosing to issue completely new hardware or if it is simply reproducing its 2019-era SKUs.

AMD released two Ryzen 3000G models back in 2019 - the 3400G and 3200G, both are quad-core Picasso APUs although the latter is lacking in simultaneous multithreading. It is not clear whether the super low budget AMD Athlon 3000G model will be included as part of the alleged 30K unit order. The 3000G series' onboard iGPUs (based on AMD's first generation Vega architecture) are likely preferred by the budget-conscious buyer since a discrete graphics card is not an essential part of builds intended for an office setting or a simple/functional home computer setup.

SK Hynix to Expand Wuxi Fab Legacy Production Capacity, Consumer DRAM Prices Struggle to Recover

Last October, the US Department of Commerce imposed semiconductor restrictions on Chinese imports of equipment for processes of 18 nm and below. SK hynix's Wuxi fab was granted a one-year production license, but geopolitical risks and weak demand prompted the company to reduce wafer starts by about 30% per month in 2Q23, according to TrendForce's latest research.

TrendForce reports that SK hynix had planned to transition its Wuxi fab's mainstream process from 1Y nm to 1Z nm, decreasing the output of legacy processes. However, due to limitations imposed by the US ban, the company instead opted to increase the share of its 21 nm production lines, focus-ing on DDR3 and DDR4 4Gb products. SK hynix's long-term strategy involves shifting its capacity expansion back to South Korea, while the Wuxi fab caters to domestic demand in China and the legacy-process consumer DRAM market.

Bosch Plans to Acquire U.S. Chipmaker TSI Semiconductors

Bosch is expanding its semiconductor business with silicon carbide chips. The technology company plans to acquire assets of the U.S. chipmaker TSI Semiconductors, based in Roseville, California. With a workforce of 250, the company is a foundry for application-specific integrated circuits, or ASICs. Currently, it mainly develops and produces large volumes of chips on 200-millimeter silicon wafers for applications in the mobility, telecommunications, energy, and life sciences industries. Over the next years, Bosch intends to invest more than 1.5 billion USD in the Roseville site and convert the TSI Semiconductors manufacturing facilities to state-of-the-art processes. Starting in 2026, the first chips will be produced on 200-millimeter wafers based on the innovative material silicon carbide (SiC).

In this way, Bosch is systematically reinforcing its semiconductor business, and will have significantly extended its global portfolio of SiC chips by the end of 2030. Above all, the global boom and ramp-up of electromobility are resulting in huge demand for such special semiconductors. The full scope of the planned investment will be heavily dependent on federal funding opportunities available via the CHIPS and Science Act as well as economic development opportunities within the State of California. Bosch and TSI Semiconductors have reached an agreement to not to disclose any financial details of the transaction, which is subject to regulatory approval.

Samsung Electronics Announces First Quarter 2023 Results, Profits Lowest in 14 Years

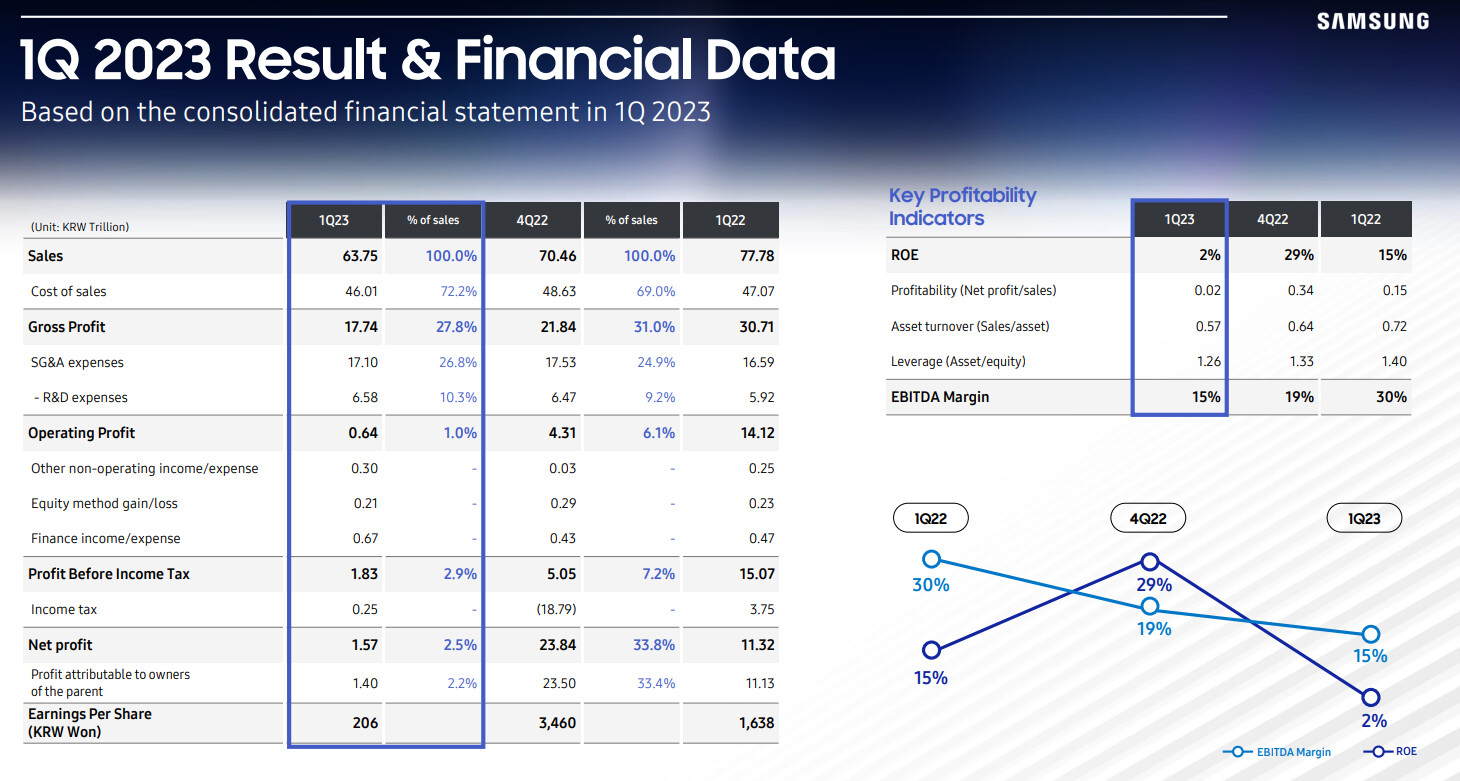
Samsung Electronics today reported financial results for the first quarter ended March 31, 2023. The Company posted KRW 63.75 trillion in consolidated revenue, a 10% decline from the previous quarter, as overall consumer spending slowed amid the uncertain global macroeconomic environment. Operating profit was KRW 0.64 trillion as the DS (Device Solutions) Division faced decreased demand, while profit in the DX (Device eXperience) Division increased.

The DS Division's profit declined from the previous quarter due to weak demand in the Memory Business, a decline in utilization rates in the Foundry Business and continued weak demand and inventory adjustments from customers. Samsung Display Corporation (SDC) saw earnings in the mobile panel business decline quarter-on-quarter amid a market contraction, while the large panel business slightly narrowed its losses. The DX Division's results improved on the back of strong sales of the premium Galaxy S23 series as well as an enhanced sales mix focusing on premium TVs.

Revenue Decline of Global Top 10 IC Design Houses Expanded to Nearly 10% in 4Q22

The global economy has faced increased inflation risks and downstream inventory corrections in 2H22, which have affected IC design houses faster than wafer foundries, as they are far more sensitive and responsive to market reversals. TrendForce reports that adverse factors such as weak overall consumption, restrictions from China, and the slowdown of corporate IT spending and CSP demand have impacted the revenue performance of the world's top 10 IC design houses in 4Q22, leading to a QoQ decline of 9.2%, or approximately US$33.96 billion.

TrendForce predicts that the revenue of these top 10 companies keep declining—though with a slight convergence—into 1Q23, owing to ongoing inventory corrections across the entire supply chain as well as Q1 being the traditional off-season for consumer demand. Demand will continue to be weak despite new product launches and inventory replenishment in the supply chain.

HBM Supply Leader SK Hynix's Market Share to Exceed 50% in 2023 Due to Demand for AI Servers

A strong growth in AI server shipments has driven demand for high bandwidth memory (HBM). TrendForce reports that the top three HBM suppliers in 2022 were SK hynix, Samsung, and Micron, with 50%, 40%, and 10% market share, respectively. Furthermore, the specifications of high-end AI GPUs designed for deep learning have led to HBM product iteration. To prepare for the launch of NVIDIA H100 and AMD MI300 in 2H23, all three major suppliers are planning for the mass production of HBM3 products. At present, SK hynix is the only supplier that mass produces HBM3 products, and as a result, is projected to increase its market share to 53% as more customers adopt HBM3. Samsung and Micron are expected to start mass production sometime towards the end of this year or early 2024, with HBM market shares of 38% and 9%, respectively.

AI server shipment volume expected to increase by 15.4% in 2023
NVIDIA's DM/ML AI servers are equipped with an average of four or eight high-end graphics cards and two mainstream x86 server CPUs. These servers are primarily used by top US cloud services providers such as Google, AWS, Meta, and Microsoft. TrendForce analysis indicates that the shipment volume of servers with high-end GPGPUs is expected to increase by around 9% in 2022, with approximately 80% of these shipments concentrated in eight major cloud service providers in China and the US. Looking ahead to 2023, Microsoft, Meta, Baidu, and ByteDance will launch generative AI products and services, further boosting AI server shipments. It is estimated that the shipment volume of AI servers will increase by 15.4% this year, and a 12.2% CAGR for AI server shipments is projected from 2023 to 2027.

Western Digital My Cloud Service Hacked, Customer Data Under Ransom

Western Digital has declared that its My Cloud online service has been compromised by a group of hackers late last month: "On March 26, 2023, Western Digital identified a network security incident involving Western Digital's systems. In connection with the ongoing incident, an unauthorized third party gained access to a number of the Company's systems. Upon discovery of the incident, the Company implemented incident response efforts and initiated an investigation with the assistance of leading outside security and forensic experts. This investigation is in its early stages and Western Digital is coordinating with law enforcement authorities."

The statement, issued on April 4, continues: "The Company is implementing proactive measures to secure its business operations including taking systems and services offline and will continue taking additional steps as appropriate. As part of its remediation efforts, Western Digital is actively working to restore impacted infrastructure and services. Based on the investigation to date, the Company believes the unauthorized party obtained certain data from its systems and is working to understand the nature and scope of that data. While Western Digital is focused on remediating this security incident, it has caused and may continue to cause disruption to parts of the Company's business operations."

CHIPS Act Requirements Untenable According to Silicon Manufacturers in South Korea and Taiwan

Silicon manufacturers in South Korea and Taiwan have questioned the requirements outlined in the United States Chips and Science Act - South Korean President Yoon Suk Yeol spoke on Thursday March 30, and said that there was a growing concern within companies Samsung Electronics Corporation and SK Hynix Inc. with regard to criteria for new U.S. semiconductor subsidies. Excess profit sharing is one area of contention, as the U.S. government will expect dividends to be paid under special conditions. The companies are also reluctant to meet the requirements of submitting detailed information about fab capacity and yield estimates. Leaders are pointing to the potential sensitive nature of exposing too much confidential corporate strategy to bodies in the USA, and sources within Samsung and SK Hynix are worried that budgetary planning information will be revealed in minute detail.

The CHIPS Act grants a $52 billion pool of research and manufacturing funds, and subsidies would be sourced from it. SK Hynix's parent group is considering an application in order to gain access to funding via the CHIPS Act, the SK Group has formed plans to invest $15 billion of its own money into the U.S. chip manufacturing sector - a North American location for an advanced chip packaging plant is being decided upon. Samsung has invested a substantial $25 billion into its Texas operation, so is eligible to receive U.S. government subsidies as well.

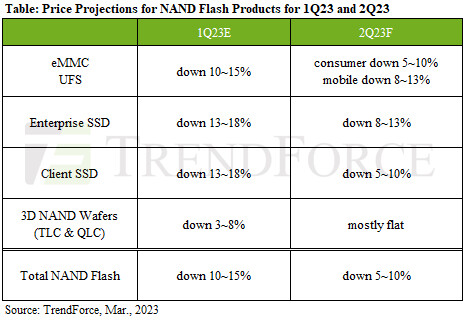
Report: ASP of NAND Flash Products Will Continue to Fall 5~10% in 2Q23, Whether Prices Continue to Decline in 2H23 Will Depend on Demand

Although NAND suppliers have continued to roll back production, there is still an oversupply of NAND Flash as demand for products such as servers, smartphones, and notebooks is still too weak. Therefore, TrendForce predicts that the ASP of NAND Flash will continue to fall in 2Q23, though that decline may shrink to 5~10%. The key to supply and demand returning to a market equilibrium lies in whether NAND suppliers can cut back on production even more. TrendForce believes if demand remains stable, then the ASP of NAND Flash will have an opportunity to rebound in 4Q23; if demand is weaker than expected, then ASP will take longer to recover.

Client SSD: Currently, PC OEM's have managed to liquidate most of their component inventory, and are now gearing up in preparation for mid-year sales events. Suppliers are cutting prices to clear out their inventories of PCIe Gen 3 SSDs, which are gradually being phased out. Meanwhile, prices of PCIe Gen 4 SSDs continue to face downward pressure due to a slow intake of new customer orders. The continuous decline of QLC products in 1Q23 has also dragged down the prices of TLC products, and there is relatively little room for prices to keep falling in 2Q23. While it still remains unclear whether or not demand will recover, TrendForce projects that the prices of PC client SSDs will drop 5~10% in 2Q23.

Decline in DRAM ASP Narrows to 10~15% in 2Q23 with No End in Sight

TrendForce reports that several suppliers, such as Micron and SK hynix, have started scaling back DRAM production. The ASP of DRAM plunged 20% in 1Q23, and this price decline is predicted to slow down to 10~15% next quarter. It's uncertain whether or not demand will recover in 2H23. Therefore, the ASP of DRAM has continued to fall as inventory levels are high from the suppliers' side, and prices will only rebound if there is a significant decrease in production.

PC DRAM: Purchase quantity from buyers has fallen drastically over the past three quarters; buyers have around 9~13 weeks of PC DRAM stock remaining. Despite suppliers having already cut production in the PC DRAM segment, DDR4 8 GB module is still likely to fall by more than 10% in 2Q23. There is a possibility that PC OEMs may purchase more DRAM because prices have been down to a relatively low level, but it is still under observation whether or not this can mitigate the inventory overstock situation from the suppliers' side. TrendForce predicts the ASP of PC DRAM will fall between 10~15%.

TSMC's 3 nm Node at Near 50 Percent Utilisation, Other Nodes Seeing Lower Demand

Based on multiple reports out of Taiwan, TSMC is seeing increased utilisation of its 3 nm node and its production line is now at close to 50 percent utilisation. The main customer here is without a doubt Apple and TSMC is churning out some 50-55,000 wafers a month on its 3 nm node. TSMC is also getting ready to start production on its N3E node later this year, which will see some customers move to the node.

However, it's not all good news, as TSMC is seeing a decline in utilisation on its 5/4 and 7/6 nm nodes as demand has dropped significantly here, with different news outlets reporting different figures. Some are suggesting the 7/6 nm nodes might have dropped as low as to 50 percent utilisation, others mention 70 percent. The 5/4 nm nodes aren't anywhere nearly as badly affected and remain at around 80 percent utilisation. The good news for TSMC is that this is expected to be a temporary slump in demand and most of its leading edge nodes should be back at somewhere around a 90 percent utilisation rate by the second half of the year. However, this depends on what the demand for its partners' products will look like going forward, as many of TSMC's customers are seeing lower demand for their products in turn.

Intel Ups Demand on Subsidies from German Government for New Fab to €5 Billion

Last month, reports were saying that Intel wanted an additional €3.2 billion from the German government in subsidies to build its fab in Magdeburg, but apparently that wasn't nearly enough, as the company has increased its demands to somewhere between €4 billion to €5 billion. What triggered Intel to go ask the German government for even more cash is most likely a combination of things, as Intel is going to want to cover increases in costs courtesy of interest hikes and the inflation that's going on globally, alongside soaring energy prices in Europe. The expected cost of the new fab is said to have increased from €17 billion to €30 billion, which is not exactly pocket change.

In a statement to Bloomberg, Intel said that "disruptions in the global economy have resulted in increased costs, from construction materials to energy," and continued "We appreciate the constructive dialogue with the federal government to address the cost gap that exists with building in other locations and make this project globally competitive." The construction start of the Magdeburg fab has already been delayed and according to Bloomberg, Intel is also considering delaying its planned assembly factory in Italy. It doesn't look promising for either party, as Intel seems to want to spend as little as possible on building its new facilities, while expecting various governments around the world to prop it up until the new facilities are making money. Hopefully neither nation will agree to Intel changing the terms of the deals, as it could cost more nations more than they would earn in long term revenue from Intel.

Shipments of AI Servers Will Climb at CAGR of 10.8% from 2022 to 2026

According to TrendForce's latest survey of the server market, many cloud service providers (CSPs) have begun large-scale investments in the kinds of equipment that support artificial intelligence (AI) technologies. This development is in response to the emergence of new applications such as self-driving cars, artificial intelligence of things (AIoT), and edge computing since 2018. TrendForce estimates that in 2022, AI servers that are equipped with general-purpose GPUs (GPGPUs) accounted for almost 1% of annual global server shipments. Moving into 2023, shipments of AI servers are projected to grow by 8% YoY thanks to ChatBot and similar applications generating demand across AI-related fields. Furthermore, shipments of AI servers are forecasted to increase at a CAGR of 10.8% from 2022 to 2026.

Revenue from Enterprise SSDs Totaled Just US$3.79 Billion for 4Q22 Due to Slumping Demand and Widening Decline in SSD Contract Prices, Says TrendForce

Looking back at 2H22, as server OEMs slowed down the momentum of their product shipments, Chinese server buyers also held a conservative outlook on future demand and focused on inventory reduction. Thus, the flow of orders for enterprise SSDs remained sluggish. However, NAND Flash suppliers had to step up shipments of enterprise SSDs during 2H22 because the demand for storage components equipped in notebook (laptop) computers and smartphones had undergone very large downward corrections. Compared with other categories of NAND Flash products, enterprise SSDs represented the only significant source of bit consumption. Ultimately, due to the imbalance between supply and demand, the QoQ decline in prices of enterprise SSDs widened to 25% for 4Q22. This price plunge, in turn, caused the quarterly total revenue from enterprise SSDs to drop by 27.4% QoQ to around US$3.79 billion. TrendForce projects that the NAND Flash industry will again post a QoQ decline in the revenue from this product category for 1Q23.

Amid Slowing PC Demand, Dell Lays Off 6,650 Employees

Dell, the global PC conglomerate, is reportedly cutting the number of its employees. The alleged move is a direct response to the economic downturn caused by declining demand for PCs, which is Dell's primary source of revenue. According to Bloomberg Intelligence, Dell is laying off about 5% of its global workforce, representing 6,650 employees from its offices. As the source notes, Dell is going under re-evaluation of its operations, and the employee headcount reduction is the affected area that will benefit the company an estimated 700 million to one billion US Dollars, as analysts predict.

IDC notes that shipments of Dell PCs have experienced the most significant decline of 37% in Q4 of 2022, compared to the same period in 2021. And given a considerable downturn, Dell's 55% of revenue from PCs is poorly affected. The company is now joining others in big tech in performing layoffs to keep profits afloat.

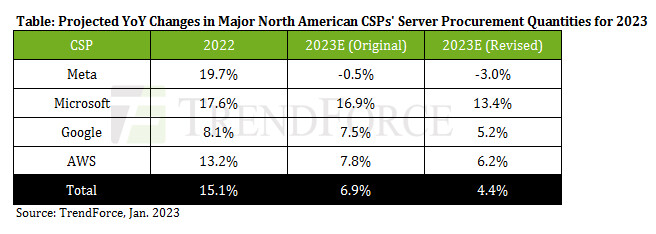
Projected YoY Growth Rate of Global Server Shipments for 2023 Has Been Lowered to 1.87% Due to North American Cloud Service Providers Cutting Demand

Facing global economic headwinds, the four major North American cloud service providers (CSPs) have scaled back their server procurement quantities for 2023 and could make further downward corrections in the future. Meta is the leader among the four in terms of server demand reduction, followed by Microsoft, Google, and AWS. TrendForce has lowered the YoY growth rate of their total server procurement quantity for this year from the original projection of 6.9% to the latest projection of 4.4%. With CSPs cutting demand, global server shipments are now estimated to grow by just 1.87% YoY for 2023. Regarding the server DRAM market, prices there are estimated to drop by around 20~25% QoQ for 1Q23 as CSPs' downward corrections exacerbate the oversupply situation.

Looking at the four CSPs individually, the YoY decline of Meta's server procurement quantity has been widened to 3.0% and could get larger. The instability of the global economy remains the largest variable for all CSPs. Besides this, Meta has also encountered a notable obstacle in expanding its operation in Europe. Specifically, its data center in Denmark has not met the regional standard for emissions. This issue is expected to hinder its progress in setting up additional data centers across the EU. Moreover, businesses related to e-commerce account for about 98% of Meta's revenue. Therefore, the decline in e-commerce activities amidst the recent easing of the COVID-19 pandemic has impacted Meta's growth momentum. Additionally, Meta's server demand has been affected by the high level of component inventory held by server ODMs.

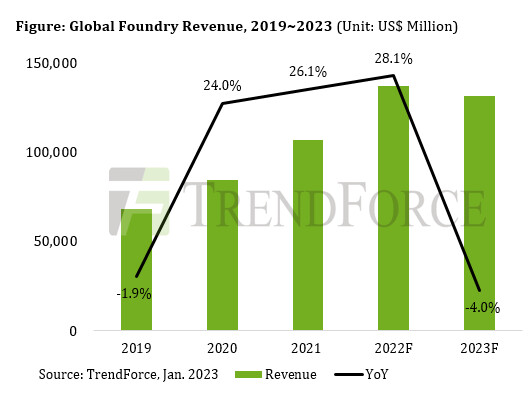
Foundry Revenue is Forecasted to Drop by 4% YoY for 2023, TrendForce Notes

TrendForce's recent analysis of the foundry market reveals that demand continues to slide for all types of mature and advanced nodes. The major IC design houses have cut wafer input for 1Q23 and will likely scale back further for 2Q23. Currently, foundries are expected to maintain a lower-than-ideal level of capacity utilization rate in the first two quarters of this year. Some nodes could experience a steeper demand drop in 2Q23 as there are still no signs of a significant rebound in wafer orders. Looking ahead to the second half of this year, orders will likely pick up for some components that underwent an inventory correction at an earlier time. However, the state of the global economy will remain the largest variable that affect demand, and the recovery of individual foundries' capacity utilization rates will not occur as quickly as expected. Taking these factors into account, TrendForce currently forecasts that global foundry revenue will drop by around 4% YoY for 2023. The projected decline for 2023 is more severe when compared with the one that was recorded for 2019.

South Korean Chip Makers Affected by Slump in Chip Demand

It's not just TSMC and the other Taiwanese chip makers that are seeing a dip in demand, the Korean chip makers have seen a slump of 15 percent in the past four months, compared to 2021. This is said to be the biggest drop in chip demand since 2009 according to data from Statistics Korea. There's a combination of factors behind the slump in demand, especially when it comes to memory related products, where inventories already are high, combined with inflation and a low demand.

According to the Financial Times, an analyst at JPMorgan in Korea isn't expecting things to improve until 2024 at the earliest. Just like Micron and Kioxia, SK hynix is looking at cutting spending on new fabs and production lines, although as TPU reported earlier this week, Samsung is going its own way, by continuing to invest in new fabs and production lines. Samsung is expected to have a capex of US$37.5 billion this year back in October, although based on the increase in costs, the capex would have increased in the fourth quarter of the year. On the plus side, it seems like the shortage of semiconductors should ease in 2023 and hopefully return to more normal levels.

Top 10 TSMC Customers Said to have Cut Orders for 2023

On the day of TSMC's celebration of the mass production start of its 3 nm node, news out of Taiwan suggests that all of its top 10 customers have cut their orders for 2023. However, the cuts are unlikely to affect its new node, but rather its existing nodes, with the 7 and 6 nm nodes said to be hit the hardest, by as much as a 50 percent utilisation reduction in the first quarter of 2023. The 28 nm and 5 and 4 nm nodes are also said to be affected, although it's unclear by how much at this point in time.

Revenue is expected to fall by at least 15 percent in the first quarter of 2023 for TSMC, based on numbers from DigiTimes. The fact that TSMC has increased its 2023 pricing by six percent should at least help offset some of the potential losses for the company, but it all depends on the demand for the rest of the year. Demand for mobile devices is down globally, which is part of the reason why so many of TSMC's customers have cut back their orders, as Apple, Qualcomm and Mediatek all produce their mobile SoCs at TSMC. Add to this that the demand for computers and new computer components are also down, largely due to the current pricing and TSMC is in for a tough time next year.

YoY Growth of NAND Flash Demand Bits Will Stay Under 30% from 2022 to 2025 as Demand Slows for PC Client SSDs, Says TrendForce

Client SSDs constituted a major driver of demand bit growth in the NAND Flash market for the past two years as the effects of the COVID-19 pandemic were spurring procurement activities related to working and studying from home. TrendForce currently projects that the attach rate of client SSDs among notebook computers will reach 92% in 2022 and around 96% in 2023. However, the demand surge related to the pandemic is subsiding, and the recent headwinds in the global economy have caused a demand freeze in the wider consumer electronics market. Hence, among the major application segments of the NAND Flash market, client SSDs are going to experience the most significant demand slowdown. This, in turn, will constrain demand bit growth as well. TrendForce projects that for the period from 2022 to 2025, the YoY growth rate of NAND Flash demand bits will remain below 30%.

The average NAND Flash content of client SSDs has already surpassed 500 GB this year. Quotes for 512 GB SSDs have fallen sharply and come to a level that is roughly comparable to the quotes that were given for 256 GB SSDs half-a-year ago. In fact, quotes for 512 GB SSDs are also near the level for HDDs with the same capacity. On the other hand, upgrading to 1 TB or higher for notebook SSDs could be challenging for PC OEMs mainly because the licensing fee for the Windows OS has a positive correlation with device specifications. Therefore, an increase in SSD capacity will raise the cost of a whole notebook computer. With PC OEMs being less keen on adopting SSDs that are 1 TB or higher, growth in the average NAND Flash content of client SSDs will also be more limited in the future.

YMTC Could Abandon Market for 3D NAND Flash by 2024 Following US Government's Decision to Place It on Entity List, Says TrendForce

Global market intelligence firm TrendForce states that Chinese memory manufacturer YMTC is now at risk of exiting the market for 3D NAND Flash products by 2024 following its formal placement on the Entity List of the US Commerce Department on December 15. From this point forward, the Commerce Department will be reviewing and approving individual transactions related to the exportation, re-exportation, and sales of equipment, technologies, and other related goods from the US to YMTC. With acquisitions of equipment parts and technical support from its US partners becoming very difficult and prolonged, YMTC is going to be severely constrained from raising its bit output. Hence, its foothold on the market for 3D NAND Flash products is expected to weaken as time goes by.

TrendForce points out that without the support of the key equipment providers, YMTC is now facing a huge technical obstacle in the development of its latest 3D NAND Flash technology known as Xtacking 3.0. In particular, raising yield rate for the 128L and 232L processes is going to be extremely challenging for the Chinese memory manufacturer. Taking account of this latest escalation in the US-China trade dispute, TrendForce has further corrected down its projections on YMTC's supply bit growth rate and the total NAND Flash supply bit growth rate for next year. YMTC supply bits were initially forecasted to grow by 60% YoY for 2023. However, there was a massive downward correction that put its growth rate at just 18%. Now, YMTC is forecasted to post a YoY decline of 7%, which is a complete reversal from the earlier projections.
Return to Keyword Browsing
Nov 11th, 2026 18:20 CST change timezone

New Forum Posts

Popular Reviews

TPU on YouTube

Controversial News Posts