Friday, September 4th 2026
Improved CPU Supply Narrows 2026 Global Notebook Shipment Decline to 9.4%, but Brands Still Face Heavy Cost Pressure
TrendForce's recent research into the notebook industry shows that CPU supply has markedly improved since 2Q26, enabling brands to gradually normalize their procurement and manufacturing processes. Meanwhile, persistent increases in DRAM and SSD costs have led brands to accelerate their procurement strategies to secure components earlier, resulting in shipment volumes exceeding expectations in the first half of the year. Nonetheless, the ongoing rise in memory prices, along with increased CPU costs, has further amplified cost pressures on notebook brands.
TrendForce notes that as CPU shortages ease in 2H26, continued advance procurement by brands, earlier replacement purchases by consumers, and stable commercial demand are expected to support an upward revision to shipment forecasts. As a result, the decline in global notebook shipments for full-year 2026 is expected to narrow to 9.4% YoY.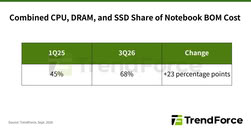 The shipment pattern in 2026 will also differ markedly from previous years, when the second half typically accounted for the peak season. With some demand originally expected in 2H26 already pulled forward into the first half, shipments are projected to be split approximately 53:47 between 1H26 and 2H26. Volumes are therefore still expected to decline beginning in the third quarter.
Core components rise to 68% of BOM costs; Cost pass-through becomes key as lower-cost inventory is depleted
TrendForce uses a mainstream model with an MSRP of US$900 in 1Q25—when memory supply was still stable—as its benchmark to assess the impact of component price increases on notebook cost structures. At the time, core components including the CPU, DRAM, and SSD accounted for approximately 45% of the system's total BOM cost. Following more than a year of price increases, this share had risen to 68% by 3Q26, underscoring how rapidly higher memory and CPU prices are reshaping notebook cost structures.
From a gross-margin perspective, the continued quarterly increases in CPU, DRAM, and SSD prices have placed even greater pressure on brands. TrendForce estimates that by 3Q26, brands would need to raise the price of a comparable 1Q25 product by approximately 80% to maintain the same gross margin as in 1Q25. This suggests that the impact of component inflation on notebook retail prices is shifting from simply increasing the cost burden to creating mounting pressure for more substantial price hikes.
TrendForce observes that brands are likely to maintain relatively aggressive shipment strategies in the near term, supported by competition for market share, new product launches, stable commercial demand, and existing inventories procured at lower costs. Advance procurement and these lower-cost inventories can also temporarily cushion the impact of rising component costs on retail prices and gross margins.
However, as lower-cost inventories across regions are gradually depleted, this cost buffer will diminish. Future products are likely to reflect current CPU, DRAM, and SSD prices to a greater extent, forcing brands to confront the trade-off between passing higher costs on to consumers and preserving demand more directly. The magnitude of retail price increases, changes in consumer replacement cycles, and brands' willingness to sacrifice margins will therefore be key factors shaping market demand going forward.
Source:
TrendForce
TrendForce notes that as CPU shortages ease in 2H26, continued advance procurement by brands, earlier replacement purchases by consumers, and stable commercial demand are expected to support an upward revision to shipment forecasts. As a result, the decline in global notebook shipments for full-year 2026 is expected to narrow to 9.4% YoY.

Core components rise to 68% of BOM costs; Cost pass-through becomes key as lower-cost inventory is depleted
TrendForce uses a mainstream model with an MSRP of US$900 in 1Q25—when memory supply was still stable—as its benchmark to assess the impact of component price increases on notebook cost structures. At the time, core components including the CPU, DRAM, and SSD accounted for approximately 45% of the system's total BOM cost. Following more than a year of price increases, this share had risen to 68% by 3Q26, underscoring how rapidly higher memory and CPU prices are reshaping notebook cost structures.
From a gross-margin perspective, the continued quarterly increases in CPU, DRAM, and SSD prices have placed even greater pressure on brands. TrendForce estimates that by 3Q26, brands would need to raise the price of a comparable 1Q25 product by approximately 80% to maintain the same gross margin as in 1Q25. This suggests that the impact of component inflation on notebook retail prices is shifting from simply increasing the cost burden to creating mounting pressure for more substantial price hikes.
TrendForce observes that brands are likely to maintain relatively aggressive shipment strategies in the near term, supported by competition for market share, new product launches, stable commercial demand, and existing inventories procured at lower costs. Advance procurement and these lower-cost inventories can also temporarily cushion the impact of rising component costs on retail prices and gross margins.
However, as lower-cost inventories across regions are gradually depleted, this cost buffer will diminish. Future products are likely to reflect current CPU, DRAM, and SSD prices to a greater extent, forcing brands to confront the trade-off between passing higher costs on to consumers and preserving demand more directly. The magnitude of retail price increases, changes in consumer replacement cycles, and brands' willingness to sacrifice margins will therefore be key factors shaping market demand going forward.
1 Comment on Improved CPU Supply Narrows 2026 Global Notebook Shipment Decline to 9.4%, but Brands Still Face Heavy Cost Pressure
I still see plenty of refurbish devices. And when you recycle, rip out parts from the second hand market, desolder the dram, etc. you drive up the prices and the sales.
There is plenty of DDR4 dram available on the second hand refurbish stores. That also includes M2 2280mm nvme
A smaller screen, double the m2 nvme =512gb, 8gib ddr4 dram sodimm, costs still the same 229€ with tax and free shipping in austria. my device, 250gb nvme, is now around 1.5years old and the 1 year refurbisher warranty is gone. it fits the w11 pro use case for generic epic game downloads and using a www-client.
I could buy 100 pieces with similar configuration for below 239€ as of now. I only checked lenovo, there are hp, dell, apple, etc also
Was it not called trade in plan, whatever? in the past? you give them your old device and you get a bit off for your next purchase?