Wednesday, July 29th 2026

Microsoft Announces Fourth Quarter Fiscal Year 2026 Results
Microsoft Corp. today announced the following results for the quarter ended June 30, 2026, as compared to the corresponding period of last fiscal year:


 "We are advancing the frontier on the cost-to-outcome curve, ensuring every customer can turn tokens into business results," said Satya Nadella, chairman and chief executive officer of Microsoft. "This year, Azure revenue surpassed $100 billion for the first time, and Microsoft 365 Copilot reached over 30 million paid seats, reflecting the confidence customers are placing in us to power their AI transformation."
"We delivered a strong quarter to close out the fiscal year, highlighted by Microsoft Cloud revenue of $59.3 billion, up 27% year-over-year," said Amy Hood, executive vice president and chief financial officer of Microsoft.
The following table adjusts for the impact from investments in OpenAI and reconciles our financial results reported in accordance with generally accepted accounting principles (GAAP) to non-GAAP financial results. Additional information regarding our non-GAAP definition is provided below. All growth comparisons relate to the corresponding period in the last fiscal year.
Business Highlights
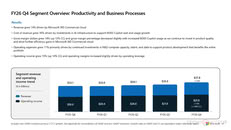
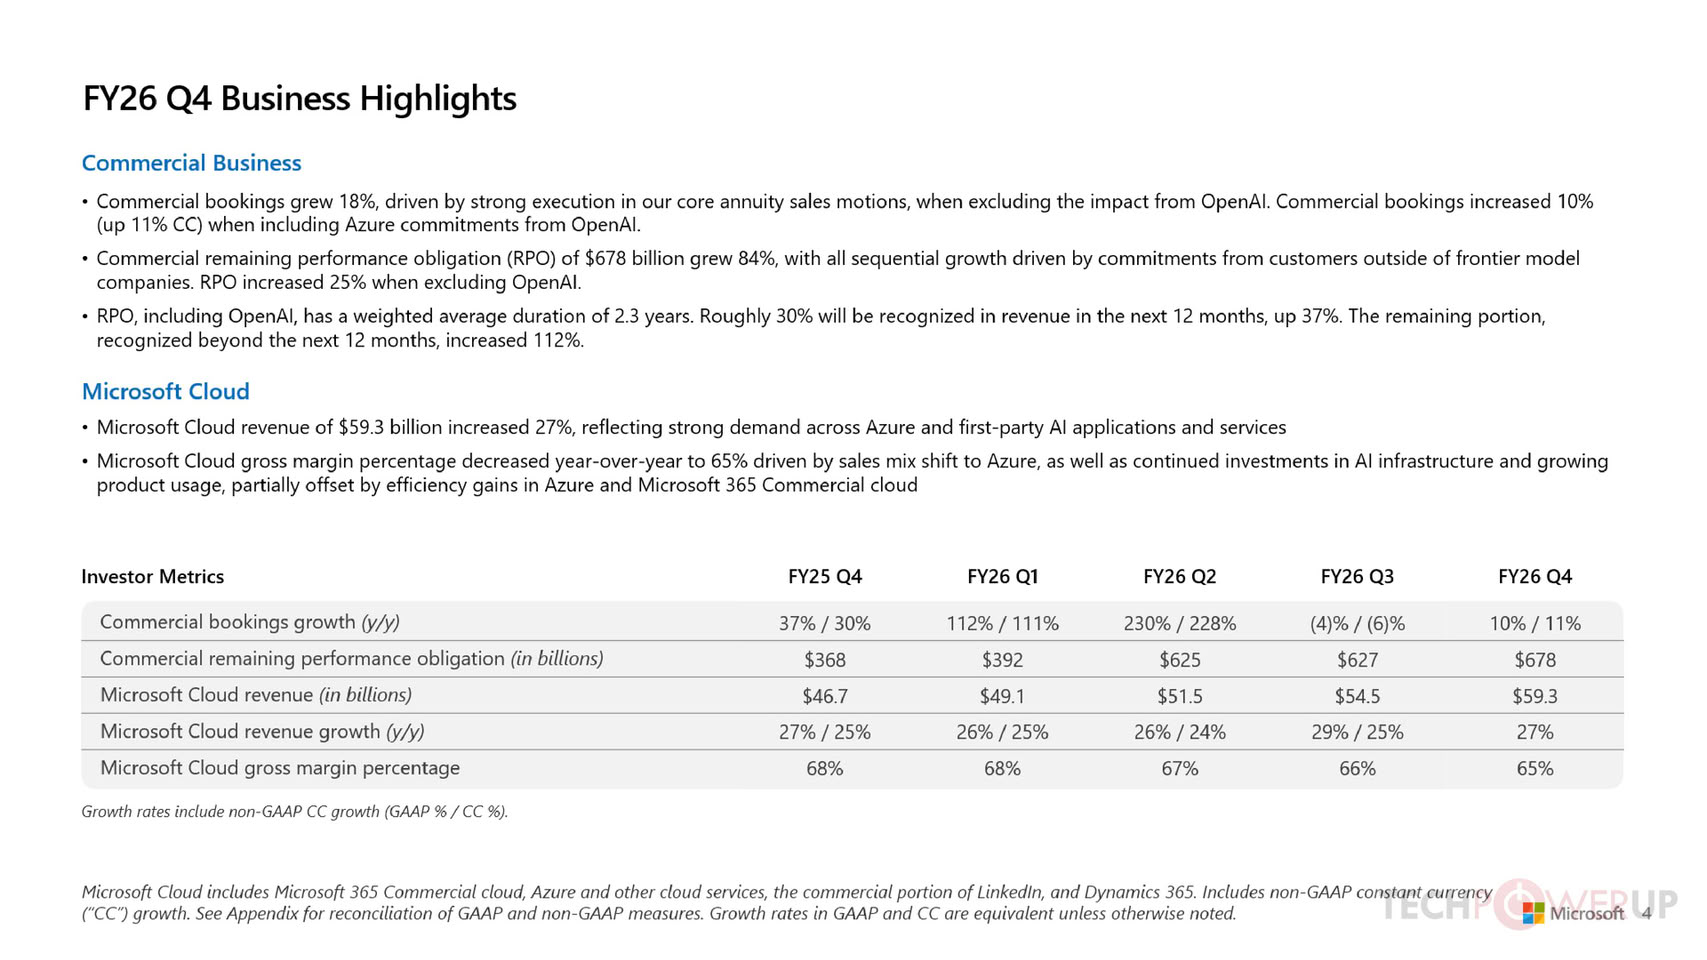
Microsoft Cloud revenue was $59.3 billion and increased 27%, and commercial remaining performance obligation increased 84% to $678 billion.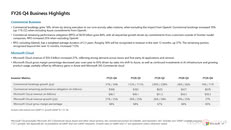 Revenue in Productivity and Business Processes was $37.8 billion and increased 14%, with the following business highlights:
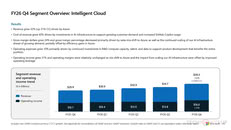
 Revenue in Intelligent Cloud was $39.3 billion and increased 32% (up 31% in constant currency), with the following business highlights:
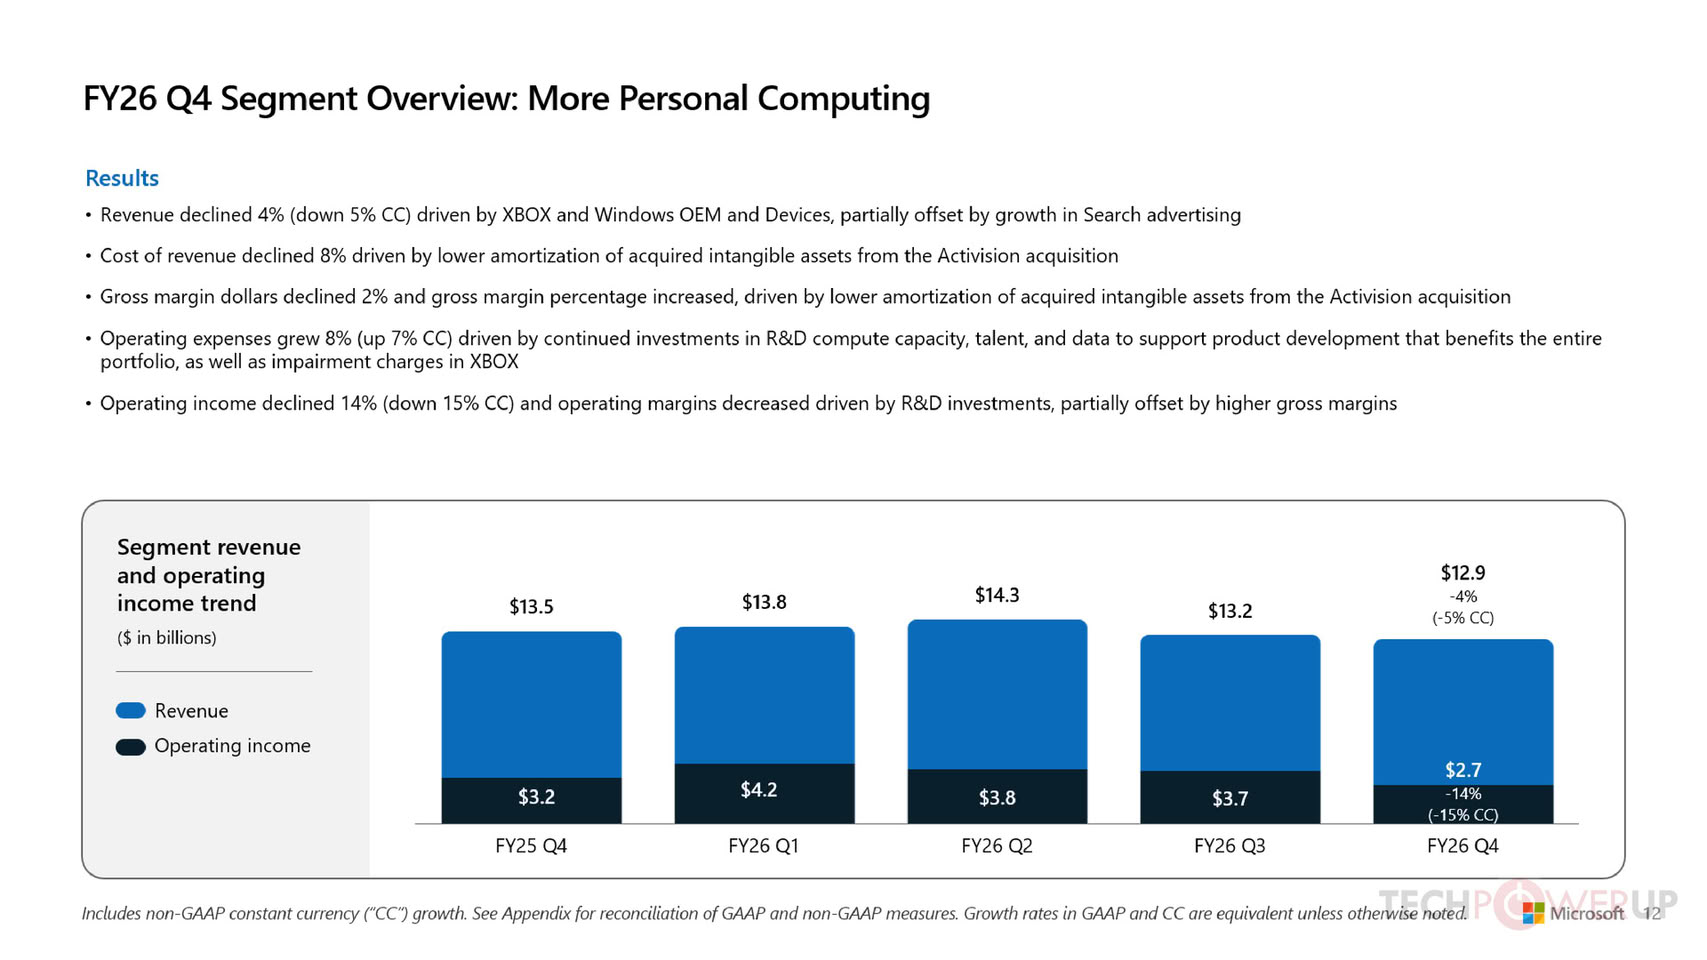
 Revenue in More Personal Computing was $12.9 billion and decreased 4% (down 5% in constant currency), with the following business highlights:
 Microsoft returned $10.2 billion to shareholders in the form of dividends and share repurchases in the fourth quarter of fiscal year 2026.
Fiscal Year 2026 Results
Microsoft Corp. today announced the following results for the fiscal year ended June 30, 2026, as compared to the corresponding period of last fiscal year:
Business Outlook
Microsoft will provide forward-looking guidance in connection with this quarterly earnings announcement on its earnings conference call and webcast.
Quarterly Highlights, Product Releases, and Customer Stories
Every quarter Microsoft delivers hundreds of products, services, and enhancements. These releases are driven by years of significant research and development investments, to empower customers with greater productivity, security, and differentiated value. This momentum is reflected in stories that showcase how our technology is shaping industries and driving customer success. We share innovation updates on our product blogs across Azure, Microsoft 365, and more on our Official Microsoft blog.
Source:
Microsoft
- Revenue was $90.0 billion and increased 18% (up 17% in constant currency)
- Operating income was $40.6 billion and increased 18%
- Net income was $35.8 billion and increased 31% on a GAAP basis, and was $35.3 billion and increased 22% on a non-GAAP basis
- Diluted earnings per share was $4.81 and increased 32% on a GAAP basis, and was $4.74 and increased 23% on a non-GAAP basis
- Non-GAAP results exclude the impact from investments in OpenAI, explained in the Non-GAAP Definition section below


"We delivered a strong quarter to close out the fiscal year, highlighted by Microsoft Cloud revenue of $59.3 billion, up 27% year-over-year," said Amy Hood, executive vice president and chief financial officer of Microsoft.
The following table adjusts for the impact from investments in OpenAI and reconciles our financial results reported in accordance with generally accepted accounting principles (GAAP) to non-GAAP financial results. Additional information regarding our non-GAAP definition is provided below. All growth comparisons relate to the corresponding period in the last fiscal year.
Business Highlights
Microsoft Cloud revenue was $59.3 billion and increased 27%, and commercial remaining performance obligation increased 84% to $678 billion.
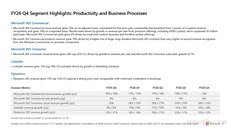
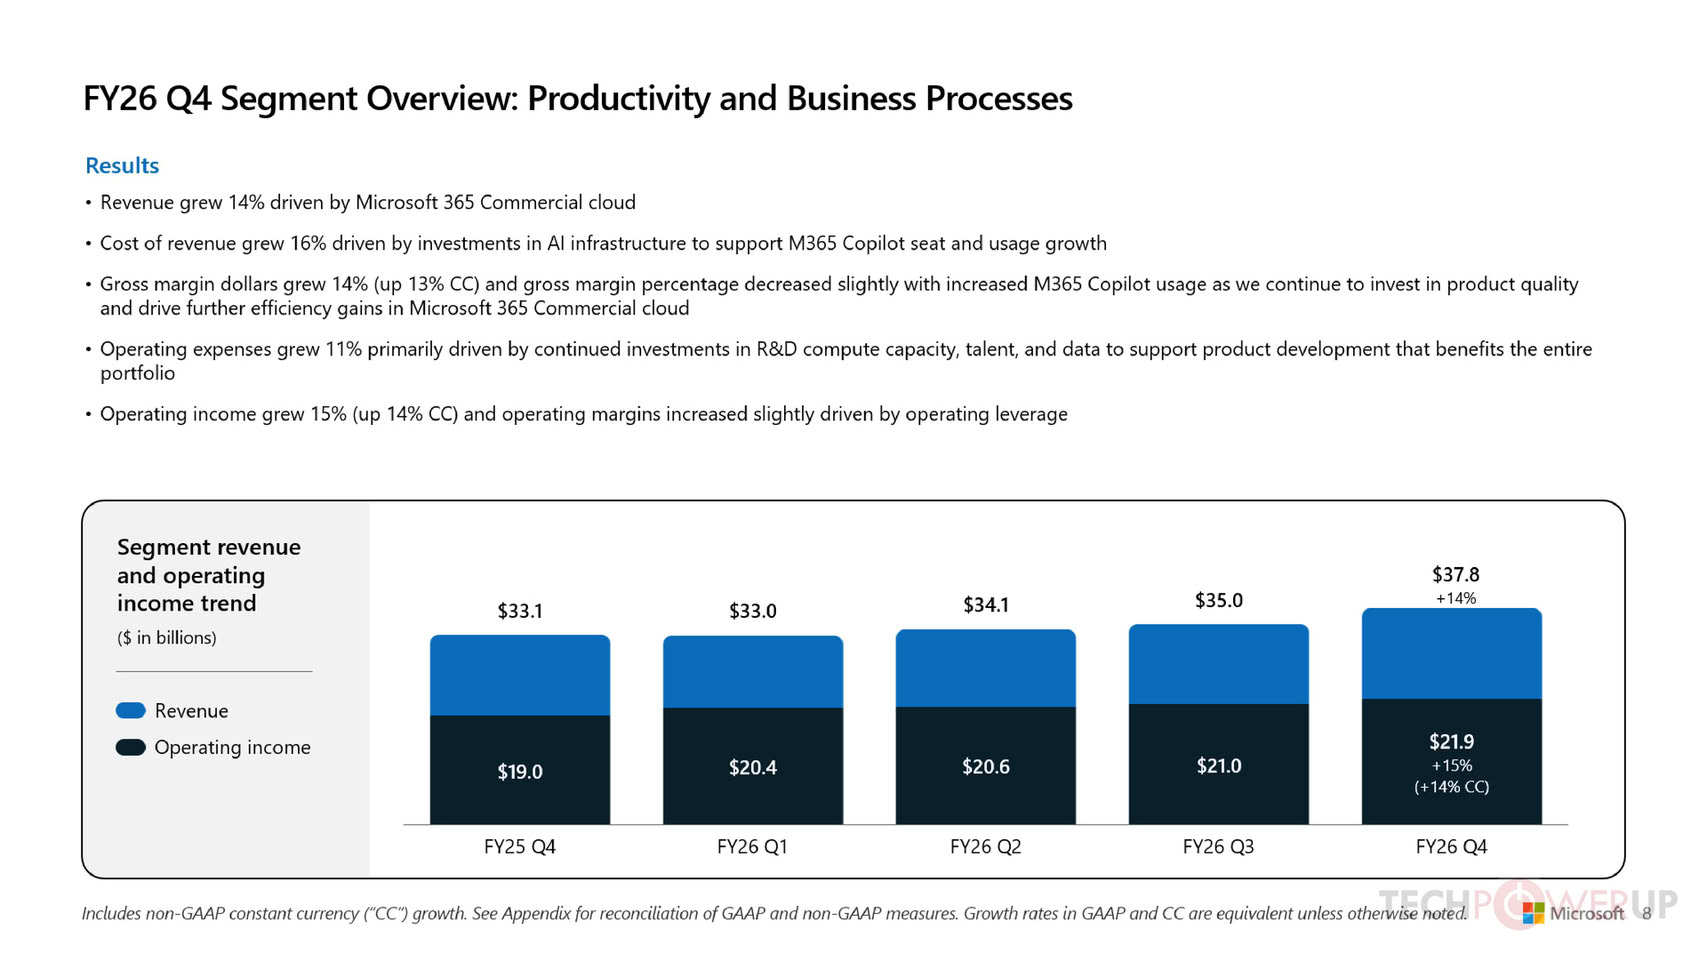
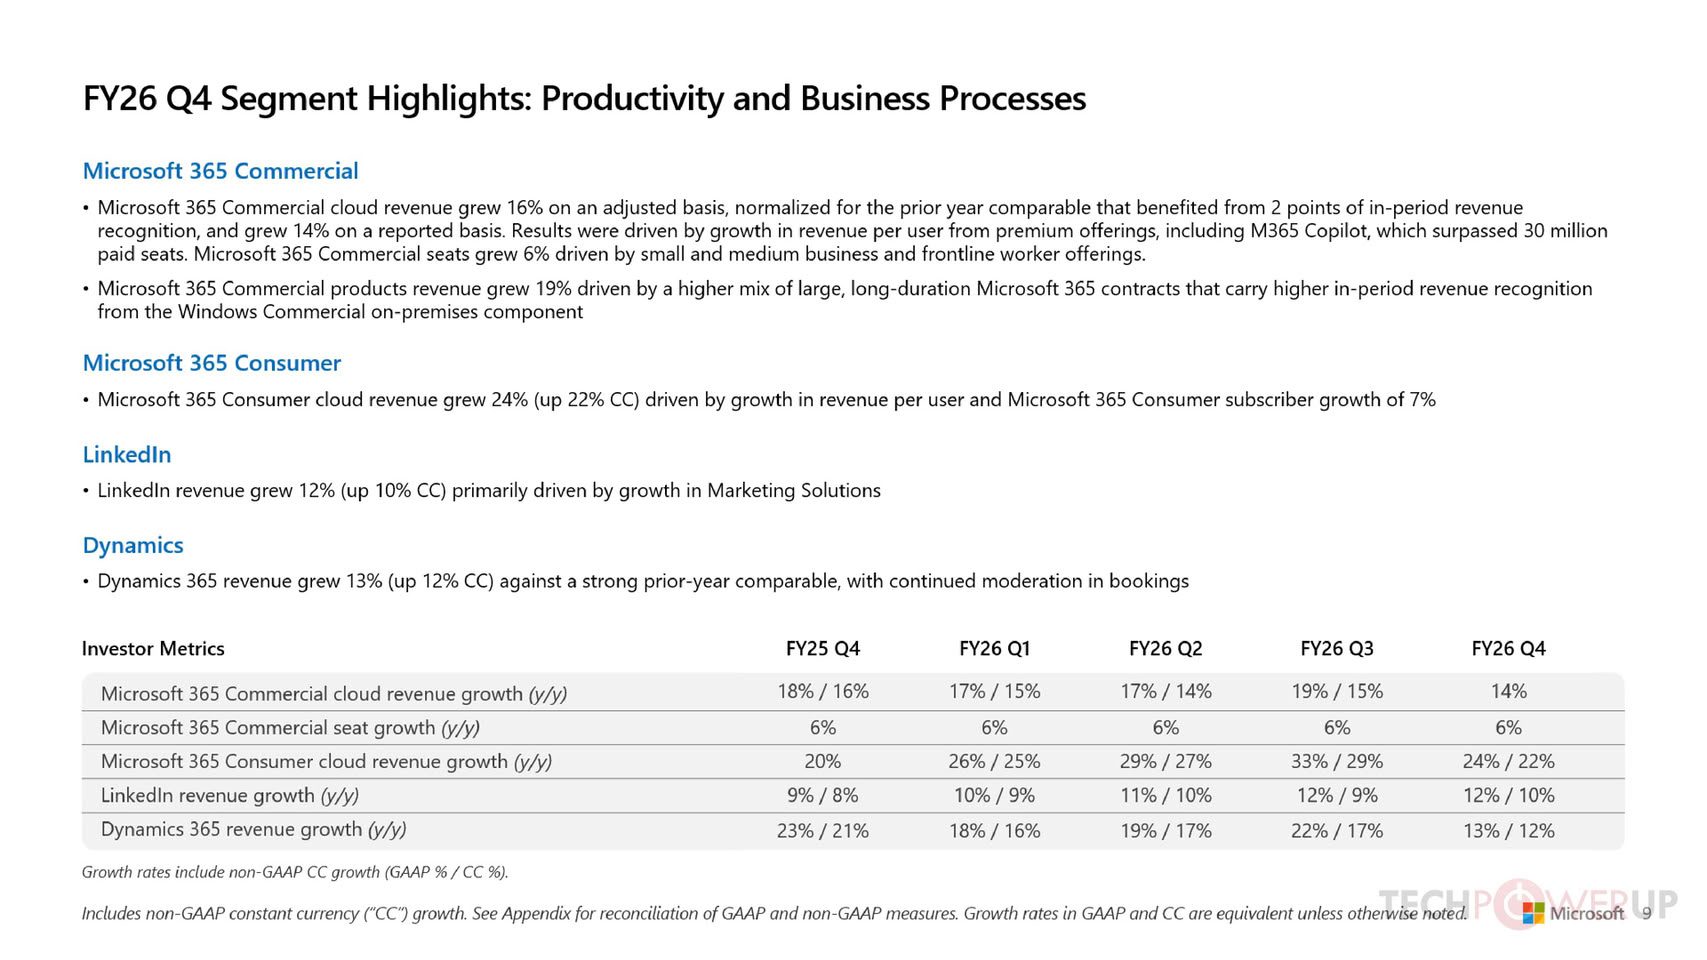
- Microsoft 365 Commercial cloud revenue increased 16% when adjusted for the prior year comparable that benefited from 2 points of in-period revenue recognition. On a reported basis, Microsoft 365 Commercial cloud revenue increased 14%.
- Microsoft 365 Consumer cloud revenue increased 24% (up 22% in constant currency)
- LinkedIn revenue increased 12% (up 10% in constant currency)
- Dynamics 365 revenue increased 13% (up 12% in constant currency)
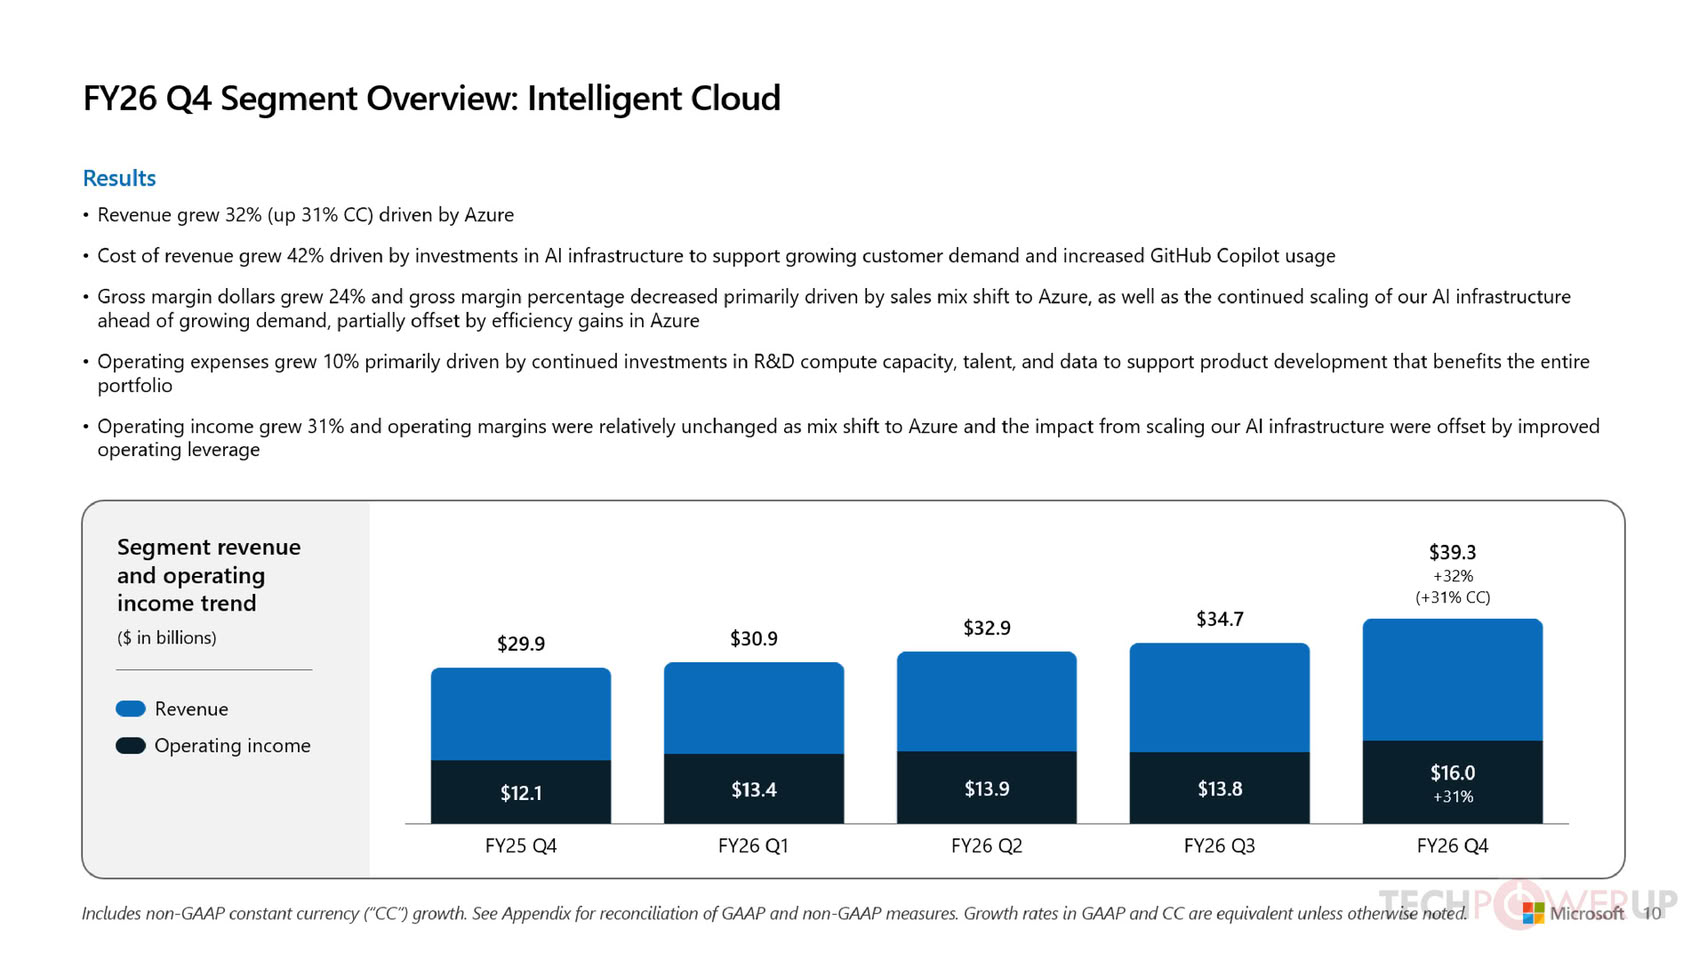
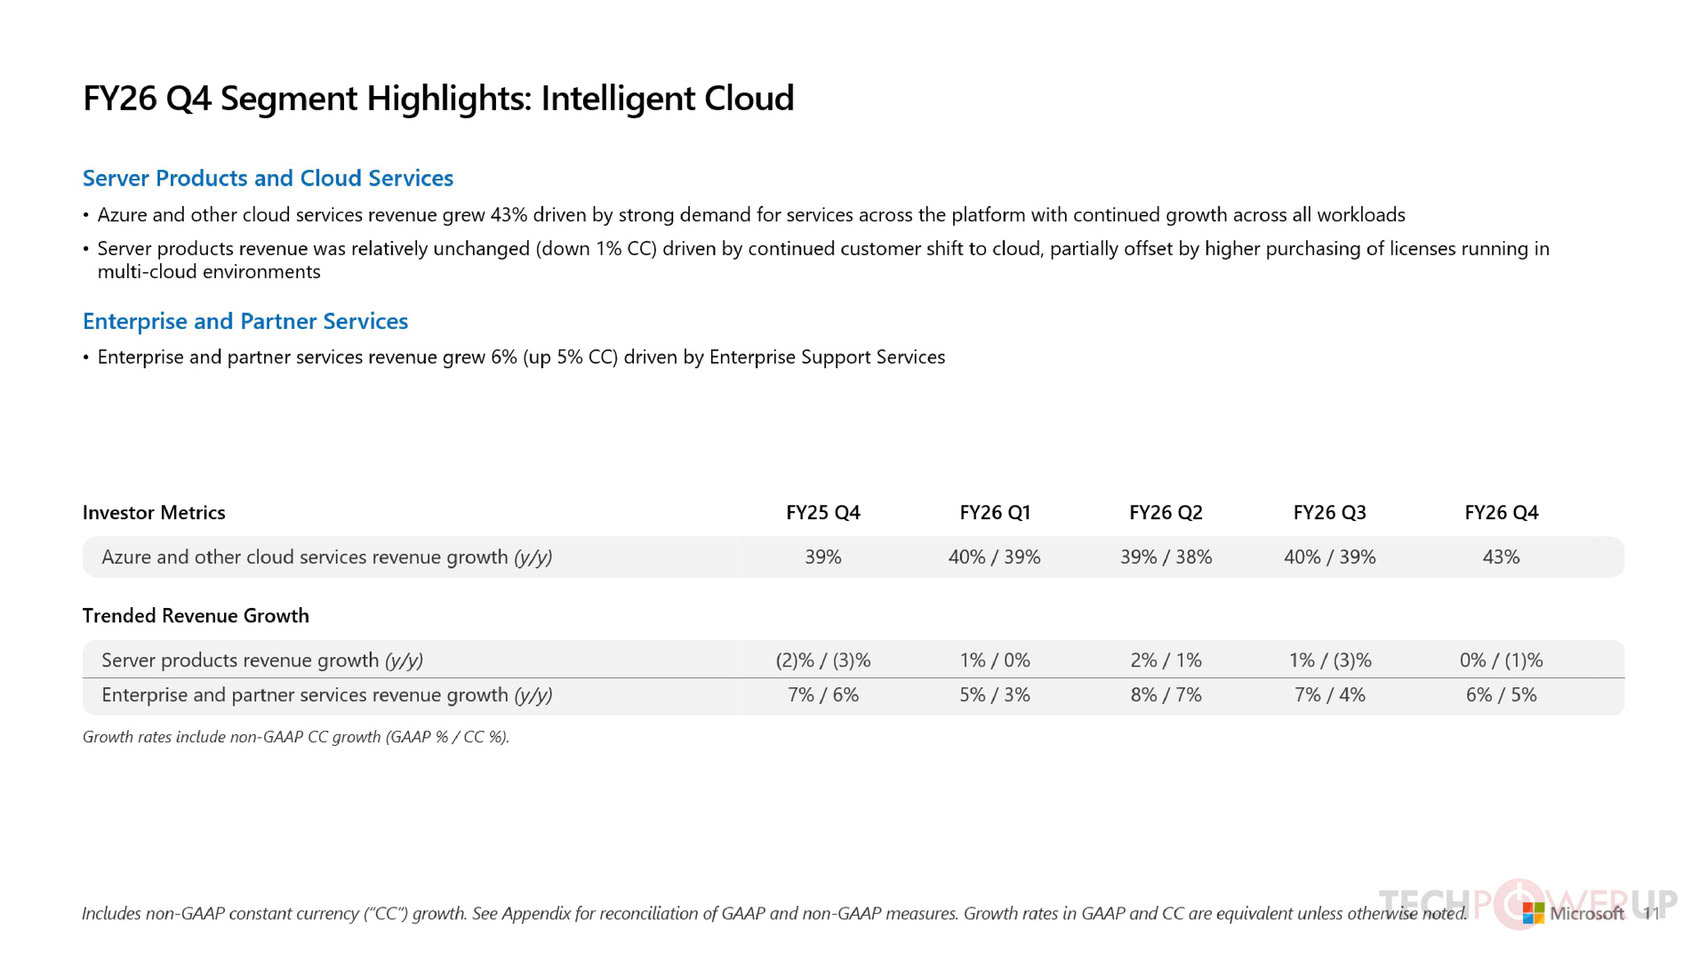
- Azure and other cloud services revenue increased 43%
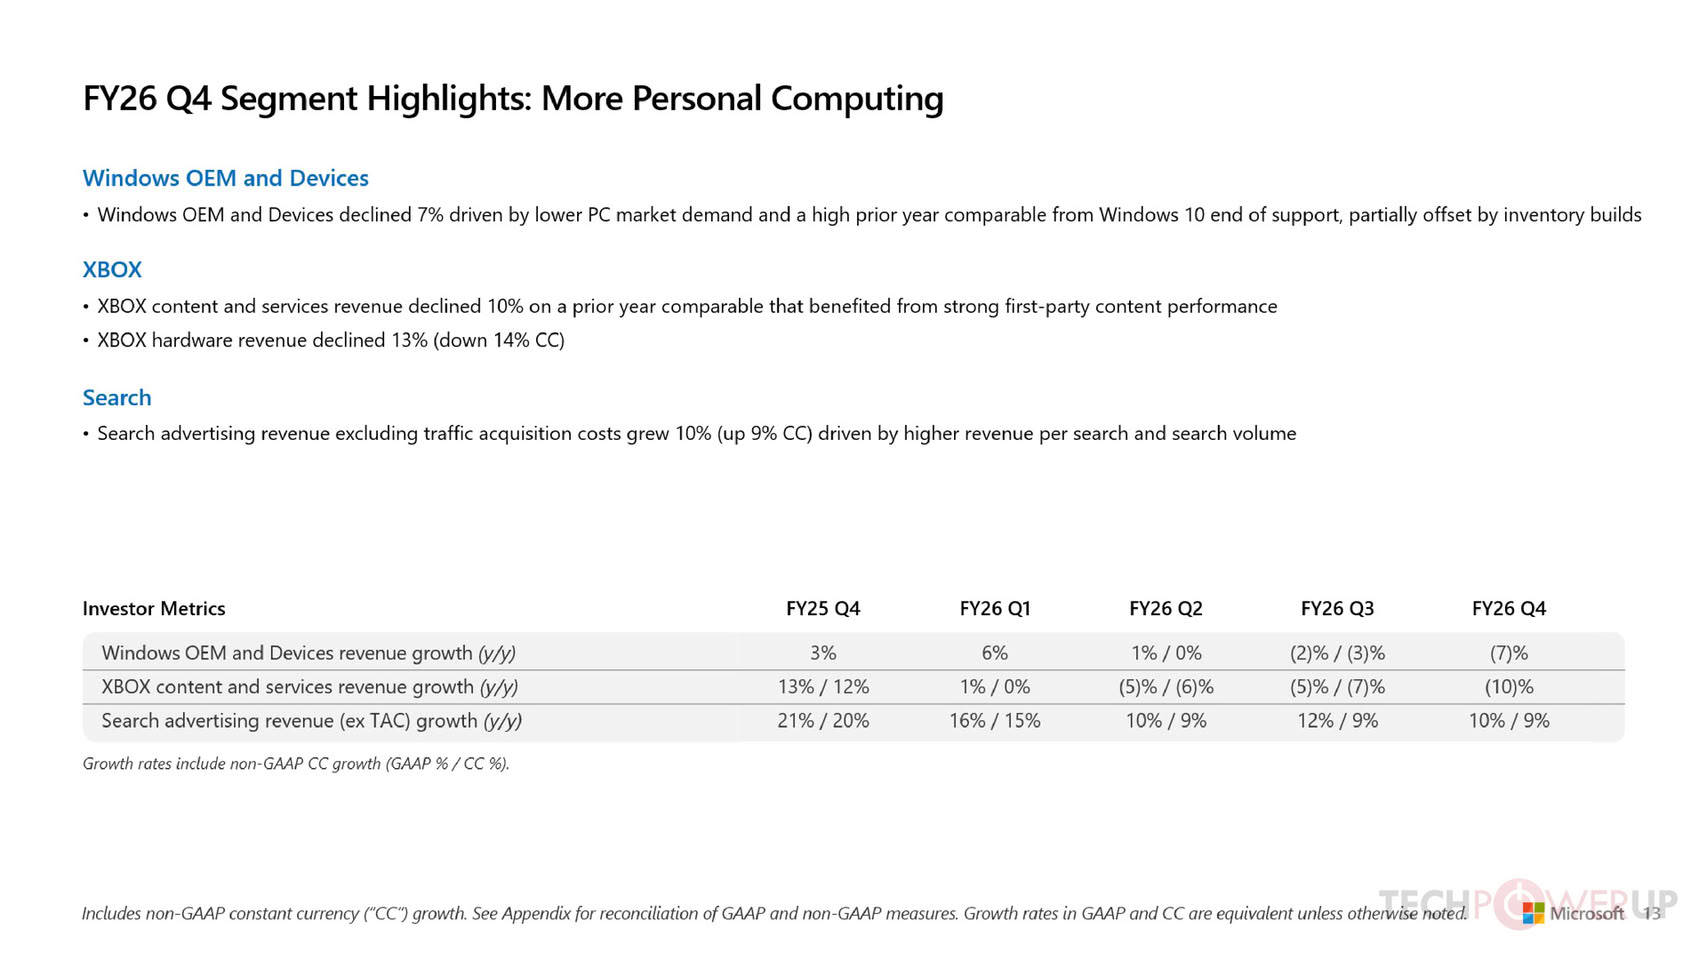
- Windows OEM and Devices revenue decreased 7%
- XBOX content and services revenue decreased 10%
- Search advertising revenue excluding traffic acquisition costs increased 10% (up 9% in constant currency)
Fiscal Year 2026 Results
Microsoft Corp. today announced the following results for the fiscal year ended June 30, 2026, as compared to the corresponding period of last fiscal year:
- Revenue was $331.8 billion and increased 18% (up 16% in constant currency)
- Operating income was $155.2 billion and increased 21% (up 19% in constant currency)
- Net income was $133.7 billion and increased 31% on a GAAP basis, and increased 22% (up 20% in constant currency) on a non-GAAP basis
- Diluted earnings per share was $17.95 and increased 32% on a GAAP basis, and increased 22% (up 21% in constant currency) on a non-GAAP basis
- Non-GAAP results exclude the impact from investments in OpenAI, explained in the Non-GAAP Definition section below
Business Outlook
Microsoft will provide forward-looking guidance in connection with this quarterly earnings announcement on its earnings conference call and webcast.
Quarterly Highlights, Product Releases, and Customer Stories
Every quarter Microsoft delivers hundreds of products, services, and enhancements. These releases are driven by years of significant research and development investments, to empower customers with greater productivity, security, and differentiated value. This momentum is reflected in stories that showcase how our technology is shaping industries and driving customer success. We share innovation updates on our product blogs across Azure, Microsoft 365, and more on our Official Microsoft blog.
6 Comments on Microsoft Announces Fourth Quarter Fiscal Year 2026 Results
I wonder if they are related in some way
Okay, so cost increases for M365 to bundle-in CoPilot at gun-point is paying-off big time, and so was shoe-horning CoPilot into every business, then suddenly stop token subsidizing on June 1st.
Minimizing in text the XBOX losses and OpenAI shenanigans wherever possible. Great work, Hood. That bonus is now assured.By "discrete": We couldn't move into enough DCs as fast as we wanted to bill more for services we couldn't get online. Also OpenAI is now burning a hole in our pockets.FriendshipEndedWithMudasir_meme.jpegSo...you negotiated down, found just cause or managed to sell the studios before firing the devs, having the now indie studios deal with the firing, in order to keep afloat? I need to read into those union claims. :shadedshu:And it might have been the 2nd-to-last report where you can say that, Staya. I'm confident businesses will not keep up with the token spending cost post FY change.By "confidence customers are placing in us" I read "no choice we're giving every customer". Sustainable? Let's see.
Not only did I not ask for this to be done without my prior consent, to add CoPilot and shove the price up, trying to renegotiate back to the now "Family Classic" actually forced my to pay the year ahead, in order to keep paying the same. I know I was not the only one. Those that did nothing, just took the price hike.
I was already burned with this, back in 2022, that made what I payed for, a lesser service.
I do not forget, Satya.
As soon as the family's dependencies are sorted, it's another contribution for the decline of subscription numbers.
- OEMs are bundling more devices without a PK bound to a UUID (makes no difference for businesses with VL, otherwise leasing from manufacturers), plus Surface is selling less, noticeably.
- As a kicker, people did buy into the Neo because of the Windows 10 EoL (besides other Apple products, Linux is up in single digit %). Nice going.
- Subscriptions are down, must be all the commotion and definitely not the stellar job done by Phill and Asha, and all the great titles being launched. /s
- Ads are everywhere in Microsoft services and products, lol.
MS isn't going anywhere, but these are not the stellar results of a company riding on the AI craze-wave. Rather flat wave, trying to be sold to seagulls, who don't even surf...just want to know if there's fish to catch.The stock rode on anticipation and closed at the same value as opening. Let's see if tomorrow is any nicer to you, Satya.
EDIT: Fixed typos. Added some stuff I had forgotten to write, while proofreading.
That is why I mentioned that this company might only throw the façade for another year, at best. Clients are not going to keep tokenmaxxing for much longer.Not if the preferred method to hire is through the EB-1 and 18 months contract at barely market values.