News Posts matching #Nanya

Return to Keyword Browsing

Terafab Wants to Become One of the Largest Memory Makers by 2032

According to Nikkei, a procurement team from Terafab, the chip venture between Tesla and SpaceX, visited Japan and walked local equipment makers through what it plans to buy. The targets it reportedly shared are gigantic: 1 million wafers per month from 2032 onward, with around 700,000 of those going to memory chips and 300,000 to logic. Nikkei's headline puts that at 40 times the output of Japan's Rapidus. The same split first surfaced in a Jiji Press report last month, which said a single Texas plant would handle both memory and logic, with a pilot fab completed as early as July 2027. Intel is reportedly helping with logic using its 2 nm and 1.4 nm-class technology, while a Taiwanese company has been floated as a technology partner for memory. That could be Nanya, though nothing is confirmed.

For context, Samsung's entire DRAM output was estimated at 650,000 to 700,000 wafers a month late last year, while SK hynix was at about 550,000 earlier this year and hopes to reach roughly 1 million by 2030 or 2031. It isn't clear whether Terafab's memory figure covers DRAM alone or also includes NAND, so the Samsung comparison is a loose one. Musk has also been careful with his own dates. On an October SpaceX call, he put "big error bars" on reaching volume production by Q3 2028, with a first SRAM test chip planned for mid-2027 at Terafab's Austin research lab.
Nanya Reports Results for Q3 2026, Revenue Increases 61.9%

Nanya Technology Corporation ("NTC", TWSE: 2408), today announced its results of operations for the third quarter, ended September 30, 2026. NTC's quarterly sales revenue was NT$133,649 million, a 61.9 percent increase compared to that in the second quarter of 2026. In the third quarter of 2026, average selling prices (ASP) increased by more than sixty percent and bit shipment decreased by mid-single digit percent quarter over quarter.

Gross profit of the quarter was NT$114,482 million; gross margin was 85.7 percent, a 6.2 percentage points improvement from that in the previous quarter. Operating income of the quarter was NT$106,894 million; operating margin was 80.0 percent; a 6.3 percentage points improvement from that in the last quarter. Non-operating income of the quarter was NT$2,438 million. The Company had net income of NT$87,627 million, with net margin of 65.6 percent.

DRAM Industry Revenue Rises 59.5% QoQ in 2Q26 as Supply Expansion Continues to Lag Demand Growth

TrendForce's latest findings on the memory industry reveal that sharp rises in traditional DRAM contract prices have led to a 59.5% QoQ increase in total DRAM industry revenue, reaching nearly US$154.73 billion in 2Q26.

Growing demand for AI servers, fueled by expanding LLM training and AI inference, has driven higher shipments of HBM3e, LPDDR5X, and high-capacity RDIMMS. The surge in agentic AI applications is further boosting RDIMM demand across various capacities.

CXMT Captures 10% of the Global DRAM Market Revenue Share

According to Counterpoint Research trackers, Chinese memory giant CXMT captured 10% of the global DRAM market share by revenue in Q2 2026, which is 150% more than the company had a year ago. On a quarterly basis, the company also experienced significant growth of 25%, as it increased its market share from 8% in Q1 to 10% in Q2. This is impressive considering the company managed to grow its revenue market share despite constrained access to advanced tooling, while established giants like Samsung, SK hynix, and Micron have undisputed access to all semiconductor manufacturing tools.

Among other DRAM makers, Samsung retains the number one spot with a 38% share, SK hynix holds 25%, and Micron is just behind at 24%. Interestingly, over the last few quarters, Samsung managed to maintain and grow its number one position, while SK hynix's share dropped from 39% a year ago to the current 25%. Micron fluctuated between 22% and the current 24%, while Nanya doubled its share from 1% to 2%.

Nanya Announces $10.7B Investment in Fab5A, Aims for 10 nm-Class EUV DRAM

Nanya Technology Board of Directors announced on August 5 that the company has launched its largest investment program, committing up to NT$346.6 billion (around $10.7 billion) to its Fab5A facility through 2026-2029. The project covers 10 nm-class processes from 1b through 1e nodes and introduces EUV lithography. Nanya has also increased its 2026 capital expenditures budget by 34% to NT$69.7 billion (around $2.16 billion). The extra NT$17.7 billion is going toward advance payments for equipment to keep Fab5A on schedule. The production roadmap has wafer starts being produced in the second half of 2027, reaching 30,000 wafers per month in 2028 and 35,900 in 2029. The maximum planned capacity is around 45,000 wafers monthly. The 1c pilot production has already begun, while the 1d node is under development and expected to enter pilot production soon. Nanya Fab5A investment, when completed, is estimated at roughly $16 billion, deployed in phases based on market demand.

Commercially, Nanya is having a strong run. July revenue hit NT$43.87 billion (around $1.3 billion), up 49.3% month over month and 719.6% year over year, driven by continued DRAM price increases, particularly sharp gains in DDR4 contract prices. Remember that just a year ago DDR4 module prices overtook DDR5 for the first time, with Nanya among the biggest beneficiaries. Its customers include giants like NVIDIA, Google, Microsoft, Intel, AMD, and Qualcomm, with the future looking great for the Taiwanese company. Its long-term agreements reportedly now cover about 50% of production capacity, with short-term contracts gradually converted into long-term agreements.

Samsung Continues DRAM Market Share Lead, Micron Is Catching Up, Notes Report

According to Counterpoint Research's Global Memory Tracker update for the second quarter of 2026, memory manufacturers are adjusting their share of the global DRAM revenue. The report highlights that South Korean memory makers remain dominant, with 65% of global DRAM revenue going to Samsung and SK hynix. Samsung holds the top position, capturing 39% of the global DRAM revenue. The South Korean giant has reportedly resolved its manufacturing issues, and its foundry has delivered strong performance, widening the gap with other manufacturers. Price increases in regular DRAM and specialty solutions like HBM have significantly boosted the company's revenue, securing its stable number one spot.

In second place, SK hynix holds about 26% of the global revenue share. This is a decrease from the 39% share the company held in Q2 2025, despite its revenue growing 214% year-over-year. This indicates that while the DRAM market is expanding, Samsung is capturing a larger share of the new market growth, leading to a higher overall revenue share. SK hynix was the first to implement long-term agreements with customers, where price volatility is predetermined. This strategy involves encouraging customers into multi-year agreements rather than capitalizing on short-term price fluctuations.

Consumer DRAM Shortages Extend to DDR2 Products with Contract Prices Expected to Continue Rising in 3Q26

TrendForce's latest research reveals that structural tightening in mature-node DRAM supply is forcing consumer DRAM buyers to adopt legacy memory products to secure larger supply allocations. This has triggered a new wave of demand for procuring older-generation DRAM components, driving continued price momentum across legacy products such as DDR2 and DDR3.

Following strong gains in 1Q26, TrendForce estimates DDR2 contract prices will rise by approximately 55-60% in 2Q26, followed by a further 35-40% increase in 3Q26.

Nanya Reports Q1 2026 Revenue Up 63%, Bit Shipments Decline Slightly

Nanya Technology Corporation ("NTC", TWSE: 2408), today announced its results of operations for the first quarter, ended March 31, 2026. Nanya's quarterly sales revenue was NT$49,087 million, a 63.1 percent increase compared to that in the fourth quarter of 2025. In the first quarter of 2026, average selling prices (ASP) increased by more than seventy percent and bit shipment decreased by mid-single digit percent quarter over quarter.

Gross profit of the quarter was NT$33,316 million; gross margin was 67.9 percent, an 18.9 percentage points improvement from that in the previous quarter. Operating income of the quarter was NT$30,111 million; operating margin was 61.3 percent; a 22.2 percentage points improvement from that in the last quarter. Non-operating income of the quarter was NT$1,607 million. The Company had net income of NT$26,058 million, with net margin of 53.1 percent. Earnings per share (EPS) was NT$8.41 (based on weighted average outstanding shares of 3,099 million). Book value per share was NT$62.25 at the quarter end. All numbers are unaudited.

DRAM Market Grows 29% in 4Q25, Samsung Regains Top Spot

TrendForce's latest findings reveal that the expansion of AI applications from LLM training to inference has prompted CSPs to broaden data center build-outs beyond AI servers to include general-purpose servers. This shift has extended memory procurement beyond HBM3e, LPDDR5X, and high-capacity RDIMMs to RDIMMs across multiple densities. Aggressive additional orders have driven a sharp increase in conventional DRAM contract prices, lifting total DRAM industry revenue to $53.58 billion in 4Q25, up 29.4% QoQ.

Across segments, buyers have struggled to secure sufficient supply amid a widening supply-demand gap. This has significantly strengthened suppliers' pricing power. Conventional DRAM contract prices rose 45-50% QoQ, while blended contract prices for conventional DRAM and HBM increased 50-55%, marking an accelerated upswing across all product categories.

Global DRAM Revenue Jumps 30.9% in 3Q25, Micron's Market Share Climbs by 3.7 Percentage Points

TrendForce's latest research shows that significant increases in conventional DRAM contract prices, higher bit shipments, and growing HBM volumes drove the global DRAM industry revenue to US$41.4 billion in 3Q25, marking a strong 30.9% QoQ growth.

Looking ahead to Q4 2025, DRAM suppliers' inventories are almost depleted, and growth in bit shipments will decrease substantially. Regarding pricing, CSPs continue to be relatively flexible with procurement costs, which causes other applications to also increase their prices to secure supply. Consequently, contract prices for both advanced and legacy nodes, as well as across all major applications, are anticipated to increase rapidly. TrendForce predicts that conventional DRAM contract prices will rise by 45-50% QoQ, and total contract prices (including DRAM and HBM) will increase by 50-55%.

2Q25 DRAM Revenue Jumps 17.1%, SK hynix Expands Market Share as Taiwanese Vendors Deliver Strong Growth

TrendForce's latest investigations demonstrate that global DRAM industry revenue reached US$31.63 billion in the second quarter of 2025, up 17.1% QoQ. This growth was fueled by rising contract prices for conventional DRAM, robust shipments growth, and expanding HBM volumes. Inventory digestion at DRAM suppliers accelerated with stronger procurement momentum from PC OEMs, smartphone makers, and CSPs, driving contract prices for most products back into positive territory.

SK hynix posted bit shipments above its targets in 2Q25. However, the higher share of lower-priced DDR4 shipments limited ASP growth. Even so, revenue surged 25.8% QoQ to $12.23 billion, boosting market share to 38.7% and securing the top spot once again.

DDR4 Module Prices Overtake DDR5 for the First Time

Usually for newer technology rollout, prices are significantly higher compared to the last-gen. However, with DRAM, the story is the opposite. For the first time since the launch of DDR5, buyers are paying more for DDR4 memory modules than for the newer standard. A combination of tariff uncertainty and rapidly depleting DDR4 inventories is the main driver behind this. TrendForce data show that some high-demand DDR4 kits rose by as much as 40% in just one week, while DRAMeXchange reports that the average spot price for a 16 Gb (1Gx16) DDR4 module at 3,200 MT/s from Samsung and SK Hynix climbed to $12.50, with peak offers hitting $24. By contrast, dual-8 Gb DDR5 kits running between 4,800 MT/s and 5,600 MT/s remain near $6 on average, rarely exceeding $9. This unexpected surge follows Micron's announcement that it will wind down DDR4 production by year's end, accelerating the depletion of existing stocks over the next six to nine months.

Samsung also announced plans earlier this spring to retire its DDR4 lines and shift its focus to DDR5 and high-bandwidth memory, while China's CXMT confirmed it will scale back its DDR4 output despite recently reaching peak production levels. Taiwan's Nanya Technology is among the biggest beneficiaries of this topsy-turvy market. In the first quarter, the company held a DDR4 inventory valued at approximately NT$37.6 billion ($1.2 billion). Nanya even paused public price quoting to manage sales at these elevated levels. Many in the tech industry worry that renewed US-China trade tensions could spark another wave of panic buying. If additional tariffs target China's remaining DDR4 supply, module costs could climb to more than three times the price of DDR5, extending this rare pricing inversion well into the next quarter.

DRAM Revenue Drops 5.5% in the First Quarter of 2025; SK hynix Overtakes Samsung for Top Spot

TrendForce's latest findings reveal that global revenue for the DRAM industry reached US$27.01 billion in 1Q25, marking a 5.5% QoQ decline. This downturn was driven by falling contract prices for conventional DRAM and a contraction in HBM shipment volumes. Samsung's redesign of its HBM3e products eased the HBM production squeezes. This prompted downstream players to clear inventories and extended the price declines seen since 4Q24.

Looking ahead to 2Q25, as PC OEMs and smartphone makers complete inventory corrections and ramp up system production ahead of the 90-day U.S. reciprocal tariff grace period, bit procurement momentum is expected to strengthen significantly. This will drive notable increases in supplier shipment volumes. On the pricing side, TrendForce forecasts a rebound across major application contract prices, with both conventional DRAM and combined DRAM (including HBM) contract prices expected to rise.

Server DRAM and HBM Continue to Drive Growth, 4Q24 DRAM Industry Revenue Increases by 9.9% QoQ

TrendForce's latest research reveals that global DRAM industry revenue surpassed US$28 billion in 4Q24, marking a 9.9% QoQ increase. This growth was primarily driven by rising contract prices for server DDR5 and concentrated shipments of HBM, leading to continued revenue expansion for the top three DRAM suppliers.

Most contract prices across applications were seen to have reversed downward. However, increased procurement of high-capacity server DDR5 by major American CSPs helped sustain price momentum for server DRAM.

Nanya Technology Reports Results for the Fourth Quarter 2024

Nanya Technology Corporation, today announced its results of operations for the fourth quarter, ended December 31, 2024. Nanya's quarterly sales revenue was NT$ 6,575 million, a 19.2 percent decrease compared to that in the third quarter of 2024. In the fourth quarter of 2024, average selling prices (ASP) decreased by low-teens percent and bit shipment decreased by high-single digit percent quarter over quarter.

Gross loss of the quarter was NT$ 695 million; gross margin was -10.6 percent, a 13.8 percentage points decrease from that in the previous quarter. Operating loss of the quarter was NT$ 2,812 million; operating margin was -42.8 percent; a 12.0 percentage points decrease from that in the last quarter. Non-operating income of the quarter was NT$ 900 million. The Company had net loss of NT$ 1,574 million, with net margin of -23.9 percent. Earnings per share (EPS) was NT$ -0.51 in the fourth quarter (based on weighted average outstanding shares of 3,099 million).

Nanya Technology Partners With PieceMakers to Develop Customized Ultra-High-Bandwidth Memory

Nanya Technology's Board of Directors today has approved a strategic partnership with PieceMakers Technology, Inc. ("PieceMakers") to jointly develop customized ultra-high-bandwidth memory solutions. As part of the collaboration, Nanya Technology will subscribe to a cash capital increase of up to NT$ 660 million, purchasing up to 22 million common shares at NT$ 30 per share in PieceMakers. Upon completion of the capital increase, Nanya Technology is expected to acquire up to approximately 38% stakes of PieceMakers.

To meet the growing demand for high-performance memory driven by AI and edge computing, this collaboration will combine Nanya Technology's 10 nm-class DRAM innovation with PieceMakers' expertise in customized DRAM design to develop high-value, high-performance, and low-power customized ultra-high-bandwidth memory solutions, unlocking new opportunities in AI and high-performance computing markets.

Kioxia Develops OCTRAM (Oxide-Semiconductor Channel Transistor DRAM) Technology

Kioxia Corporation, a world leader in memory solutions, today announced the development of OCTRAM (Oxide-Semiconductor Channel Transistor DRAM), a new type of 4F2 DRAM, comprised of an oxide-semiconductor transistor that has a high ON current, and an ultra-low OFF current, simultaneously. This technology is expected to realize a low power DRAM by bringing out the ultra-low leakage property of the InGaZnO transistor. This was first announced at the IEEE International Electron Devices Meeting (IEDM) held in San Francisco, CA on December 9, 2024. This achievement was jointly developed by Nanya Technology and Kioxia Corporation. This technology has the potential to lower power consumption in a wide range of applications, including AI and post-5G communication systems, and IoT products.

The OCTRAM utilizes a cylinder-shaped InGaZnO vertical transistor (Fig.1) as a cell transistor. This design enables the adaptation of a 4F2 DRAM, which offers significant advantages in memory density compared to the conventional silicon-based 6F2 DRAM.

Server DRAM and HBM Boost 3Q24 DRAM Industry Revenue by 13.6% QoQ

TrendForce's latest investigations reveal that the global DRAM industry revenue reached US$26.02 billion in 3Q24, marking a 13.6% QoQ increase. The rise was driven by growing demand for DDR5 and HBM in data centers, despite a decline in LPDDR4 and DDR4 shipments due to inventory reduction by Chinese smartphone brands and capacity expansion by Chinese DRAM suppliers. ASPs continued their upward trend from the previous quarter, with contract prices rising by 8% to 13%, further supported by HBM's displacement of conventional DRAM production.

Looking ahead to 4Q24, TrendForce projects a QoQ increase in overall DRAM bit shipments. However, the capacity constraints caused by HBM production are expected to have a weaker-than-anticipated impact on pricing. Additionally, capacity expansions by Chinese suppliers may prompt PC OEMs and smartphone brands to aggressively deplete inventory to secure lower-priced DRAM products. As a result, contract prices for conventional DRAM and blended prices for conventional DRAM and HBM are expected to decline.

Nanya and Winbond Boost Memory Production Amid Rising Demand and Prices

As memory prices and volumes increase, manufacturers Nanya and Winbond have ceased the production cuts they implemented last year, with production now back to normal levels. Market research agencies and supply chain analysts indicate that memory shipments are expected to continue recovering in Q3 2024. Currently, memory factories are operating at a capacity utilization rate of 90% to full capacity, which is significantly higher than the 60% to 70% capacity utilization rate of wafer foundries with mature processes. Last year, Nanya adjusted its production volume reducing it by up to 20%. This year, production has gradually increased, reaching 70% to over 80% in the second quarter, and has now resumed normal levels.

Nanya anticipates that DRAM market conditions and prices will improve quarter by quarter, with the overall industry trending positively, potentially turning losses into profits in the third quarter. Nanya announced yesterday that its consolidated revenue for June was 3.363 billion yuan, marking a monthly increase of 0.35% and an annual increase of 36.83%, setting a high for the year. The cumulative consolidated revenue for the first half of the year was 19.424 billion yuan, a 44.4% increase compared to the same period last year. Nanya will hold a press conference on July 10 to announce its second-quarter financial results and operating outlook.

Contract Price Increases Offset Seasonal Slump, Boosting DRAM Q1 Revenue by 5.1%

TrendForce reveals that the DRAM industry experienced a 5.1% revenue increase in 1Q24 compared to the previous quarter. This growth—reaching US$18.35 billion—was driven by rising contract prices for mainstream products, with the price increase being more significant than in 4Q23. As a result, most companies in the industry continued to see revenue growth.

The top three suppliers experienced a decline in shipments in the first quarter, demonstrating the industry's off-season effect. Additionally, downstream companies had higher inventory levels, which led to a significant reduction in procurement volume. As for ASP, the top three suppliers continued to benefit from contract price increases seen in 4Q23. With inventory levels still healthy, there was a strong intention to raise prices.

DRAM Manufacturers Gradually Resume Production, Impact on Total Q2 DRAM Output Estimated to Be Less Than 1%

Following in the wake of an earthquake that struck on April 3rd, TrendForce undertook an in-depth analysis of its effects on the DRAM industry, uncovering a sector that has shown remarkable resilience and faced minimal interruptions. Despite some damage and the necessity for inspections or disposal of wafers among suppliers, the facilities' strong earthquake preparedness of the facilities has kept the overall impact to a minimum.

Leading DRAM producers, including Micron, Nanya, PSMC, and Winbond had all returned to full operational status by April 8th. In particular, Micron's progression to cutting-edge processes—specifically the 1alpha and 1beta nm technologies—is anticipated to significantly alter the landscape of DRAM bit production. In contrast, other Taiwanese DRAM manufacturers are still working with 38 and 25 nm processes, contributing less to total output. TrendForce estimates that the earthquake's effect on DRAM production for the second quarter will be limited to a manageable 1%.

DRAM Industry Sees Nearly 30% Revenue Growth in 4Q23 Due to Rising Prices and Volume

TrendForce reports a 29.6% QoQ in DRAM industry revenue for 4Q23, reaching US$17.46 billion, propelled by revitalized stockpiling efforts and strategic production control by leading manufacturers. Looking ahead to 1Q24, the intent to further enhance profitability is evident, with a projected near 20% increase in DRAM contract prices—albeit with a slight decrease in shipment volumes to the traditional off-season.

Samsung led the pack with the highest revenue growth among the top manufacturers in Q4 as it jumped 50% QoQ to hit $7.95 billion, largely due to a surge in 1alpha nm DDR5 shipments, boosting server DRAM shipments by over 60%. SK hynix saw a modest 1-3% rise in shipment volumes but benefited from the pricing advantage of HBM and DDR5, especially from high-density server DRAM modules, leading to a 17-19% increase in ASP and a 20.2% rise in revenue to $5.56 billion. Micron witnessed growth in both volume and price, with a 4-6% increase in each, resulting in a more moderate revenue growth of 8.9%, totaling $3.35 billion for the quarter due to its comparatively lower share of DDR5 and HBM.

Contract Prices Bottom Out in Q3, Reigniting Buyer Momentum and Boosting DRAM Revenue by Nearly 20%, Notes Report

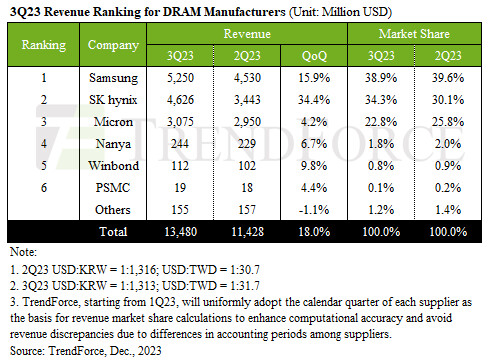
TrendForce investigations reveal a significant leap in the DRAM industry for 3Q23, with total revenues soaring to US$13.48 billion—marking 18% QoQ growth. This surge is attributed to a gradual resurgence in demand, prompting buyers to re-energize their procurement activities. Looking ahead to Q4, while suppliers are firmly set on price hikes, with DRAM contract prices expected to rise by approximately 13-18%, demand recovery will not be as robust as in previous peak seasons. Overall, while there is demand for stockpiling, procurement for the server sector remains tentative due to high inventory levels, suggesting limited growth in DRAM industry shipments for Q4.

Three major manufacturers witnessed Q3 revenue growth. Samsung's revenue increased by about 15.9% to US$5.25 billion thanks to stable demand for high-capacity products fueled by AI advancements and the rollout of its 1alpha nm DDR5. SK hynix showcased the most notable growth among manufacturers with a 34.4% increase, reaching about US$4.626 billion and significantly narrowing its market share gap with Samsung to less than 5%. Micron's revenue rose by approximately 4.2% to US$3.075 billion—despite a slight drop in ASP—supported by an upswing in demand and shipment volumes.

Q2 DRAM Industry Revenue Rebounds with a 20.4% Quarterly Increase, Q3 Operating Profit Margin Expected to Turn from Loss to Gains

TrendForce reports that rising demand for AI servers has driven growth in HBM shipments. Combined with the wave of inventory buildup for DDR5 on the client side, the second quarter saw all three major DRAM suppliers experience shipment growth. Q2 revenue for the DRAM industry reached approximately US$11.43 billion, marking a 20.4% QoQ increase and halting a decline that persisted for three consecutive quarters. Among suppliers, SK hynix saw a significant quarterly growth of over 35% in shipments. The company's shipments of DDR5 and HBM, both of which have higher ASP, increased significantly. As a result, SK hynix's ASP grew counter-cyclically by 7-9%, driving its Q2 revenue to increase by nearly 50%. With revenue reaching US$3.44 billion, SK hynix claimed the second spot in the industry, leading growth in the sector.

Samsung, with its DDR5 process still at 1Ynm and limited shipments in the second quarter, experienced a drop in its ASP by around 7-9%. However, benefitting from inventory buildup by module houses and increased demand for AI server setups, Samsung saw a slight increase in shipments. This led to an 8.6% QoQ increase in Q2 revenue, reaching US$4.53 billion, securing them the top position. Micron, ranking third, was a bit late in HBM development. However, DDR5 shipments held a significant proportion, keeping their ASP relatively stable. Boosted by shipments, its revenue was around US$2.95 billion, a quarterly increase of 15.7%. Both companies saw a reduction in their market share.

DRAM Industry Q1 Revenues Decline 21.2% QoQ, Marking Third Consecutive Quarter of Downturn

TrendForce reports a dramatic 21.2% QoQ decline in Q1 revenues for the DRAM industry, bringing total revenue down to US$9.663 billion. This significant dip represents the third consecutive quarter where revenues have fallen. A closer look reveals that increased shipment volumes were exclusive to Micron, with other suppliers noting a decrease. The ASP fell for all three major suppliers. An enduring oversupply issue, which has led to an ongoing slump in prices, is the chief culprit behind the decline. Nevertheless, the industry expects a gradual slowing in the rate of price decline following planned production cuts. TrendForce's Q2 forecast suggests a rise in shipments, but the ongoing price fall might limit potential revenue growth.

Each of the three major suppliers—Samsung, Micron, and SK hynix—reported a drop in quarterly revenue. Samsung saw a decline in both shipment volumes and ASP due to fewer orders for its newly launched devices, resulting in a QoQ decrease in revenue of 24.7%, amounting to about US$4.17 billion. Benefiting from its earlier financial reporting and the tail-end orders of the previous year, Micron climbed to the second position in 1Q23. Despite being the only supplier among the big three to record positive shipment growth, Micron couldn't avoid a minor 3.8% revenue decline, taking its total down to US$2.72 billion. SK hynix faced the steepest decline, with more than a 15% drop in both shipment volume and ASP, leading to a drastic 31.7% plunge in revenue, amounting to approximately USD$2.31 billion.
Return to Keyword Browsing
Nov 11th, 2026 07:07 CST change timezone

New Forum Posts

Popular Reviews

TPU on YouTube

Controversial News Posts