News Posts matching #DDR3

Return to Keyword Browsing

NVIDIA Marks 20 Years of the GeForce 8800 GTX With a Free Path-Traced Steam Demo

NVIDIA is celebrating 20 years of the GeForce 8800 GTX, which hit store shelves on November 8, 2006, with a free tech demo on Steam. Called GeForce 8800 GTX - 20 Years of a Legend, it was created by Unreal Engine artist Dylan Browne, the developer of Through The Ages, with support from NVIDIA. The semi-interactive demo puts players in a 2006-era PC gaming room, where they can unbox the 8800 GTX, inspect it up close, and install it in an era-accurate PC tower, with GeForce easter eggs scattered around. The scene is rendered with path tracing, DLSS 4.5 Ray Reconstruction, Dynamic Multi Frame Generation, and RTX Mega Geometry. It is available now on Steam and is coming soon to GeForce NOW for Ultimate members.

Naturally, the 8800 GTX itself can't run any of this, which is quite ironic, to say the least. Steam lists an RTX 4070 as the bare minimum and recommends an RTX 5080, alongside 32 GB of system RAM and 30 GB of storage. That RAM figure alone is over 40 times the 8800 GTX's 768 MB of video memory. The recommended RTX 5080 is far from cheap right now either, with TechSpot's October survey putting its lowest US price at around $2,200. So a demo built around the thrill of unboxing a new GPU in 2006 wants one of the priciest gaming cards of 2026 to look its best.
Intel Core i5-4670K Gets a New Cinebench R11.5 Record, 13 Years After Launch

Overclocker Luumi has taken the top spot in HWBot's Cinebench R11.5 rankings for the Intel Core i5-4670K, beating a record that had stood for around 12 years. Running the 2013 Haswell quad-core at 6,301 MHz under liquid nitrogen, Luumi scored 10.8 cb, just edging out Strat's previous 10.76 cb at 6,249 MHz. That's roughly 66% above the chip's 3.8 GHz boost clock, which is quite a lot for a four-core, four-thread part built on Intel's 22 nm process. The top of the leaderboard is tight as well, with Moose83 sitting third at 10.74 cb out of 187 submissions. Of course, this is a record for the i5-4670K category, not an overall Cinebench R11.5 world record. Luumi also has a history with Cinebench, having set an 8-core world record on an EVGA Z390 Dark back in 2018.

The test bench was period-correct too. Luumi used an ASRock Z97 OC Formula, the same board that pushed a Core i7-4790K past 7 GHz back in 2014, along with 4 GB of XPG DDR3 running at 2,708 MT/s with 8-12-7-28 timings and a Corsair AXi 1600 power supply. The run was done on Windows 7, as HWBot's R11.5 rules apparently don't allow pre-Skylake Intel chips on newer versions of Windows without BenchMate. Haswell is no stranger to extreme clocks, as the Core i7-4770K was overclocked to 7 GHz before it even launched in 2013. A modern 12-core laptop reportedly scores around four times higher in R11.5 while running in quiet mode, so the achievement here is about squeezing every last megahertz out of 13-year-old silicon.

DRAM Industry Revenue Rises 59.5% QoQ in 2Q26 as Supply Expansion Continues to Lag Demand Growth

TrendForce's latest findings on the memory industry reveal that sharp rises in traditional DRAM contract prices have led to a 59.5% QoQ increase in total DRAM industry revenue, reaching nearly US$154.73 billion in 2Q26.

Growing demand for AI servers, fueled by expanding LLM training and AI inference, has driven higher shipments of HBM3e, LPDDR5X, and high-capacity RDIMMS. The surge in agentic AI applications is further boosting RDIMM demand across various capacities.

Consumer DRAM Shortages Extend to DDR2 Products with Contract Prices Expected to Continue Rising in 3Q26

TrendForce's latest research reveals that structural tightening in mature-node DRAM supply is forcing consumer DRAM buyers to adopt legacy memory products to secure larger supply allocations. This has triggered a new wave of demand for procuring older-generation DRAM components, driving continued price momentum across legacy products such as DDR2 and DDR3.

Following strong gains in 1Q26, TrendForce estimates DDR2 contract prices will rise by approximately 55-60% in 2Q26, followed by a further 35-40% increase in 3Q26.

Limited Capacity and Order Shifts Drive March Consumer DRAM Price Surge, Led by Sub-4Gb Products

Major suppliers are continuing to phase out production of mature products below DDR4, according to TrendForce's latest research on the memory industry. As supply tightens structurally, DRAM prices have already posted significant cumulative increases in recent months.

TrendForce forecasts that consumer DRAM contract prices will continue to rise by 45-50% QoQ in 2Q26 after taking into account ongoing supply reductions, order transfers, and the slower pace of capacity expansion among Taiwanese suppliers.

Steam Will Estimate Game FPS Before Purchase to Show Expected PC Performance

Steam is reportedly in the process of adding a "Frame Estimator" tool that can estimate your PC's performance before you purchase a game. As you know, Valve's Steam platform is the largest gaming platform in the world, with access to millions of PCs. The Steam Client application offers an option to include your PC in Valve's telemetry system, which processes data such as your PC's specifications and game information, including your library. Using these data points, Steam will estimate how many frames per second your PC can generate in any game, depending on your configuration. For example, for a specific CPU, GPU, and available system memory, the Steam Client will indicate whether a game can reach 60 FPS at 1440p using high settings, or whatever your preference is. We can only speculate at this point about what the feature will look like, as Steam is still refining it before the public beta release.

Additionally, Valve has already started asking users for anonymous FPS data collection about a month ago whenever they run a game. With this data pool, likely involving millions of participants, Valve aims to build a system that estimates your FPS output based on your specific PC configuration, without needing to run a game first. Reportedly, this feature will appear in the Steam Client and show how much performance your PC can deliver before you even purchase a game. This is a classic recommendation system that will indicate what your configuration typically delivers at specific game settings and resolutions.

DRAM Market Grows 29% in 4Q25, Samsung Regains Top Spot

TrendForce's latest findings reveal that the expansion of AI applications from LLM training to inference has prompted CSPs to broaden data center build-outs beyond AI servers to include general-purpose servers. This shift has extended memory procurement beyond HBM3e, LPDDR5X, and high-capacity RDIMMs to RDIMMs across multiple densities. Aggressive additional orders have driven a sharp increase in conventional DRAM contract prices, lifting total DRAM industry revenue to $53.58 billion in 4Q25, up 29.4% QoQ.

Across segments, buyers have struggled to secure sufficient supply amid a widening supply-demand gap. This has significantly strengthened suppliers' pricing power. Conventional DRAM contract prices rose 45-50% QoQ, while blended contract prices for conventional DRAM and HBM increased 50-55%, marking an accelerated upswing across all product categories.

DDR3 Platforms Make a Comeback Amid Severe Memory Shortages

The year is 2007 2026 and DDR3 memory platforms are becoming popular. Amid a severe memory shortage, technology nearly two decades old is rising in demand as consumers struggle to find modern memory at reasonable prices. According to a report from Chinese Board Channels, Chinese consumers are turning to Intel's old X99 HEDT platform as a way to obtain high memory capacity at a good price. Older Intel Xeon processors offer quad-channel memory, and Chinese aftermarket motherboards have adapted regular DDR3 and ECC DDR3 memory to work with the X99 chipset, which originally supports DDR4 memory, allowing the reuse of older, cheaper modules. With quad-channel support and up to 128 GB of capacity, this approach provides workstation-grade capacity at a fraction of the price. Additionally, we found listings of dual-socket X99 motherboards with LGA 2011-V3 sockets, which offer DDR3 capacity of up to 256 GB across eight total channels.
Board ChannelsThere is one major trend worth watching: DDR3 motherboard sales are growing quickly. This may be driven by a rebound in demand for lower priced builds. Bundles that pair DDR3 motherboards with 6th to 9th gen CPUs are selling well. Based on recent information from domestic motherboard brands, DDR3 motherboard volumes are rising fast, showing a rapid growth trend of roughly 2 to 3 times or more.

DRAM Prices to Continue Rising in 4Q25, Server Demand Surges Ahead While Legacy Process Products See Steeper Increases

TrendForce's latest investigations reveal that the three major DRAM suppliers continue to allocate advanced process capacity primarily to high-end server DRAM and HBM, crowding out capacity for PC, mobile, and consumer applications. Combined with diverging demand across end products, this dynamic is keeping legacy-process DRAM price hikes pronounced, while newer-generation products are seeing more modest gains. Overall, conventional DRAM prices are expected to rise 8-13% QoQ in 4Q25, and when HBM is included, the increase could widen to 13-18%.

PC DRAM prices edge up slightly, U.S. CSPs consider early server DRAM procurement
Shipments of finished PCs are projected to decline with PC promotions and restocking momentum slowing in 4Q25, leading major OEMs to cut DRAM bit procurement. Meanwhile, as the three suppliers aggressively shift capacity toward server DDR5, the supply of both PC DDR5 and DDR4 remains constrained. As a result, PC DRAM prices are forecast to continue edging upward through the quarter.
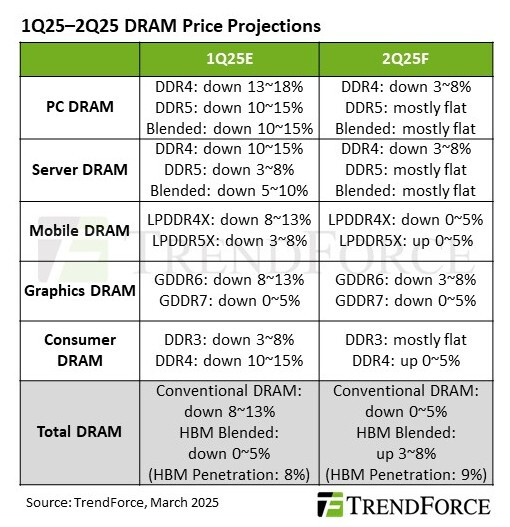
Downstream Inventory Reduction Eases DRAM Price Decline in 2Q25

TrendForce's latest findings reveal that U.S. tariff hikes prompted most downstream brands to frontload shipments to 1Q25, accelerating inventory reduction across the memory supply chain. Looking ahead to the second quarter, conventional DRAM prices are expected to decline by just 0-5% QoQ, while average DRAM pricing including HBM is forecast to rise by 3-8%, driven by increasing shipments of HBM3e 12hi.

PC and server DRAM prices to hold steady
In response to potential U.S. tariff hikes, major PC OEMs are requesting ODMs to increase production, accelerating DRAM depletion in their inventories. OEMs with lower inventory levels may raise procurement from suppliers in Q2 to ensure stable DRAM supply for the second half of 2025.

Top DRAM Manufacturers Touted to End DDR3 & DDR4 Production in 2025

Inside sources—familiar with goings-ons at leading DRAM manufacturing firms—have predicted the end of DDR3 and DDR4 production lines. According to a DigiTimes Asia report (citing Nikkei), industry observers have noticed that the DRAM market is undergoing a so-called "shift." They believe that pricing trends are decreasing due to weak demand. Samsung Electronics, SK Hynix, and Micron are named as major players; allegedly involved in devising new strategies—in reaction to fluid market circumstances. The DigiTimes insider network proposes that the big three: "may phase out DDR3 and DDR4 by 2025...by the end of 2025...anticipating a future focused on advanced memory technologies." Older standards are falling out of favor, with DDR5 and high-bandwidth memory (HBM) on the ascent. Industry watchdogs reckon that possible DDR3 and DDR4 supply shortages could occur "post-summer 2025."

Taiwan's Nanya Technology has predicted that the overall DRAM market will "bottom out" within the first half of 2025. An eventual recovery is envisioned by the second quarter; AI-related demands could help drive up demand by a large margin. Additionally, Nanya points to improved inventory management and global economic stimulus. Taiwanese DRAM production houses are expected to pick up some slack, but an unnamed "key component distributor" anticipates serious after-effects. An anonymous source believes that the: "anticipated halt in production could lead to significant supply constraints, challenging market dynamics and impacting pricing strategies." Nanya Technology and Winbond Electronics produce specialized DRAM-types; therefore are not touted to be great gap fillers. The latter is reportedly reacting to weak demand for "mature" DDR products—DigiTimes commented on this development: "Winbond Electronics is advancing its manufacturing by transitioning to a 16 nm process in the latter half of 2025. This upgrade from the current 20 nm process, primarily used for 4 Gb DDR3 and DDR4, will enable Winbond to produce 8 Gb DDR memory."

Passive Buyer Strategies Drive DRAM Contract Prices Down Across the Board in 1Q25

TrendForce's latest investigations reveal that the DRAM market is expected to face downward pricing pressure in 1Q25 as seasonal weakness aligns with sluggish consumer demand for products like smartphones. Additionally, early stockpiling by notebook manufacturers—over potential import tariffs under the Trump administration—has further exacerbated the pricing decline.

Conventional DRAM prices are projected to drop by 8% to 13%. However, if HBM products are included, the anticipated price decline will range from 0% to 5%.

Slowing Demand Growth Constrains Q4 Memory Price Increases

TrendForce's latest findings reveal that weaker consumer demand has persisted through 3Q24, leaving AI servers as the primary driver of memory demand. This dynamic, combined with HBM production displacing conventional DRAM capacity, has led suppliers to maintain a firm stance on contract price hikes.

Smartphone brands continue to remain cautious despite some server OEMs continuing to show purchasing momentum. Consequently, TrendForce forecasts that Q4 memory prices will see a significant slowdown in growth, with conventional DRAM expected to increase by only 0-5%. However, benefiting from the rising share of HBM, the average price of overall DRAM is projected to rise 8-13%—a marked deceleration compared to the previous quarter.

DDR4 Remains a Popular Memory Standard: TechPowerUp Poll

Back in July, we polled our readers to find out what PC main memory type they are using, with the choices consisting of DDR5, DDR4, and DDR3. Nearly two months into the poll and close to 36,000 responses later, an interesting picture is emerging. DDR4 memory emerged a clear winner, with a simple majority of our readers—58.2% of them—responding that they're using it. The latest DDR5 memory type is a distant second, with close to one-third of the respondents or 32.5% picking it. The old DDR3 memory type attracted an impressive 9.3% of the vote.

There could be many reasons why DDR4 remains the king—the AMD AM4 platform remains current, as AMD continues to release processors for this platform. Intel's LGA1700 platform supports DDR4, and there's a fairly wide selection of DDR4 motherboards for this platform, letting enthusiasts save on memory costs by carrying over their old memory or opting for cheaper memory. DDR5 at 32% isn't too discouraging, considering that the standard has been around just 3 years now, compared to the 9 years of DDR4.

DRAM Prices Expected to Increase by 8-13% in Q3

TrendForce reports that a recovery in demand for general servers—coupled with an increased production share of HBM by DRAM suppliers—has led suppliers to maintain their stance on hiking prices. As a result, the ASP of DRAM in the third quarter is expected to continue rising, with an anticipated increase of 8-13%. The price of conventional DRAM is expected to rise by 5-10%, showing a slight contraction compared to the increase in the second quarter.

TrendForce notes that buyers were more conservative about restocking in the second, and inventory levels on both the supplier and buyer sides did not show significant changes. Looking ahead to the third quarter, there is still room for inventory replenishment for smartphones and CSPs, and the peak season for production is soon to commence. Consequently, it is expected that smartphones and servers will drive an increase in memory shipments in the third quarter.

DRAM Manufacturers Gradually Resume Production, Impact on Total Q2 DRAM Output Estimated to Be Less Than 1%

Following in the wake of an earthquake that struck on April 3rd, TrendForce undertook an in-depth analysis of its effects on the DRAM industry, uncovering a sector that has shown remarkable resilience and faced minimal interruptions. Despite some damage and the necessity for inspections or disposal of wafers among suppliers, the facilities' strong earthquake preparedness of the facilities has kept the overall impact to a minimum.

Leading DRAM producers, including Micron, Nanya, PSMC, and Winbond had all returned to full operational status by April 8th. In particular, Micron's progression to cutting-edge processes—specifically the 1alpha and 1beta nm technologies—is anticipated to significantly alter the landscape of DRAM bit production. In contrast, other Taiwanese DRAM manufacturers are still working with 38 and 25 nm processes, contributing less to total output. TrendForce estimates that the earthquake's effect on DRAM production for the second quarter will be limited to a manageable 1%.

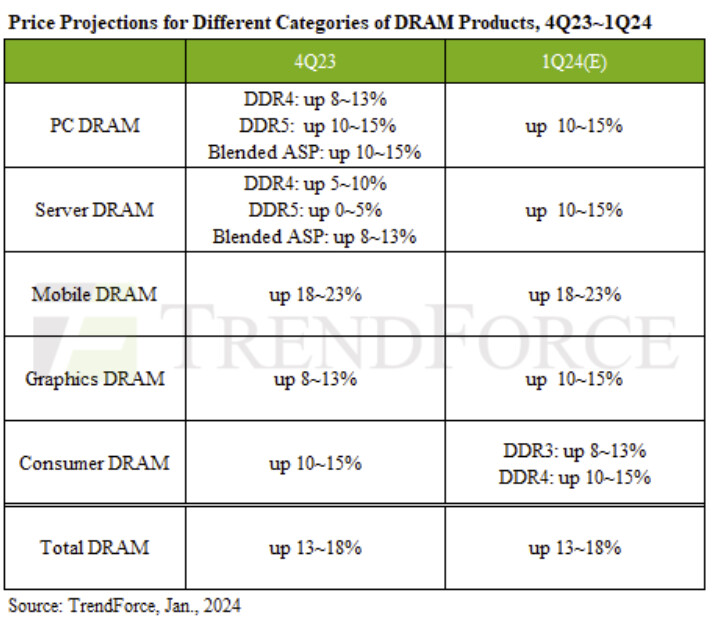
DRAM Contract Prices Projected to Increase 13-18% in 1Q24 as Price Surge Continues

TrendForce reports that the DRAM contract prices are estimated to increase by approximately 13-18% in 1Q24 with mobile DRAM leading the surge. It appears that due to the unclear demand outlook for the entire year of 2024, manufacturers believe that sustained production cuts are necessary to maintain the supply-demand balance in the memory industry.

PC DRAM: The market is buzzing with unfilled DDR5 orders, while savvy buyers brace for a continued surge in DDR4 prices, keeping procurement engines running. This trend, however, is shadowed by a gradual industry pivot toward DDR5, casting uncertainty over the expansion of DDR4 bit procurement volumes. Despite this, both DDR4 and DDR5 prices have yet to hit the target set by manufacturers, and buyers seem ready to ride the wave of price hikes into 1Q24. This sets the stage for an estimated 10-15% in PC DRAM contract prices, with DDR5 poised to take the lead over DDR4 in this pricing rally.

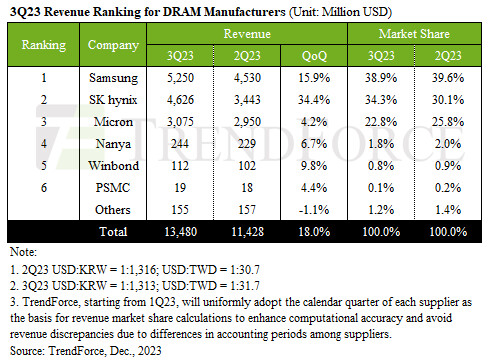
Contract Prices Bottom Out in Q3, Reigniting Buyer Momentum and Boosting DRAM Revenue by Nearly 20%, Notes Report

TrendForce investigations reveal a significant leap in the DRAM industry for 3Q23, with total revenues soaring to US$13.48 billion—marking 18% QoQ growth. This surge is attributed to a gradual resurgence in demand, prompting buyers to re-energize their procurement activities. Looking ahead to Q4, while suppliers are firmly set on price hikes, with DRAM contract prices expected to rise by approximately 13-18%, demand recovery will not be as robust as in previous peak seasons. Overall, while there is demand for stockpiling, procurement for the server sector remains tentative due to high inventory levels, suggesting limited growth in DRAM industry shipments for Q4.

Three major manufacturers witnessed Q3 revenue growth. Samsung's revenue increased by about 15.9% to US$5.25 billion thanks to stable demand for high-capacity products fueled by AI advancements and the rollout of its 1alpha nm DDR5. SK hynix showcased the most notable growth among manufacturers with a 34.4% increase, reaching about US$4.626 billion and significantly narrowing its market share gap with Samsung to less than 5%. Micron's revenue rose by approximately 4.2% to US$3.075 billion—despite a slight drop in ASP—supported by an upswing in demand and shipment volumes.

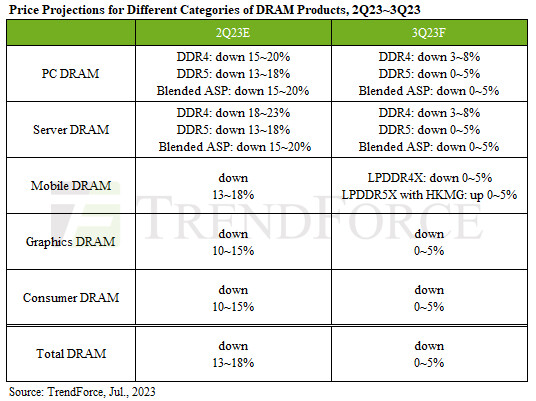
DRAM ASP Decline Narrows to 0~5% for 3Q23 Owing to Production Cuts and Seasonal Demand

TrendForce reports that continued production cuts by DRAM suppliers have led to a gradual quarterly decrease in overall DRAM supply. Seasonal demand, on the other hand, is helping to mitigate inventory pressure on suppliers. TrendForce projects that the third quarter will see the ASP for DRAM converging towards a 0~5% decline. Despite suppliers' concerted efforts, inventory levels persistently remain high, keeping prices low. While production cutbacks may help to curtail quarterly price declines, a tangible recovery in prices may not be seen until 2024.

PC DRAM: The benefits of consolidated production cuts on DDR4 by the top three suppliers are expected to become evident in the third quarter. Furthermore, inventory pressure on suppliers has been partially alleviated due to aggressive purchasing by several OEMs at low prices during 2Q23. Evaluating average price trends for PC DRAM products in 3Q23 reveals that DDR4 will continue to remain in a state of persistent oversupply, leading to an expected quarterly price drop of 3~8%. DDR5 prices—influenced by suppliers' efforts to maintain prices and unmet buyer demand—are projected to see a 0-5% quarterly decline. The overall ASP of PC DRAM is projected to experience a QoQ decline of 0~5% in the third quarter.

SK Hynix to Expand Wuxi Fab Legacy Production Capacity, Consumer DRAM Prices Struggle to Recover

Last October, the US Department of Commerce imposed semiconductor restrictions on Chinese imports of equipment for processes of 18 nm and below. SK hynix's Wuxi fab was granted a one-year production license, but geopolitical risks and weak demand prompted the company to reduce wafer starts by about 30% per month in 2Q23, according to TrendForce's latest research.

TrendForce reports that SK hynix had planned to transition its Wuxi fab's mainstream process from 1Y nm to 1Z nm, decreasing the output of legacy processes. However, due to limitations imposed by the US ban, the company instead opted to increase the share of its 21 nm production lines, focus-ing on DDR3 and DDR4 4Gb products. SK hynix's long-term strategy involves shifting its capacity expansion back to South Korea, while the Wuxi fab caters to domestic demand in China and the legacy-process consumer DRAM market.

GELID Solutions IceROCK DDR Cooling Kit Available Now

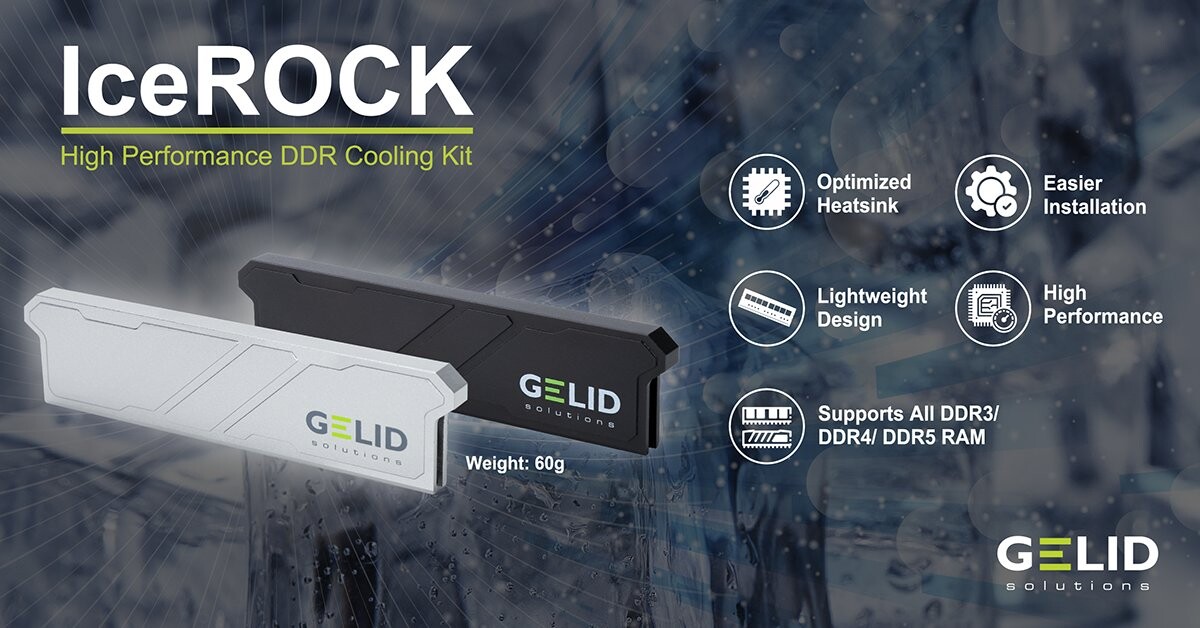
GELID Solutions has introduced its brand new IceROCK DDR Cooling Kit to the world. This aftermarket heatsink radiator is constructed from high-grade aluminium and available to order in two finishes - black or silver. These kits offers primary support for DDR5 memory modules, but Gelid has made sure to provide full compatibility for older DDR3 and DDR4 RAM sticks. The optimized heatsink is light in weight and easy to install, and offers professional level cooling - ideal for overclocking and boosting enthusiasts.

The minimalist and sleek design only weighs in at 60 g, and the pure and high-grade aluminium heatsink guarantees excellent heat conductivity. The kit can be installed onto a wide variety of memory module shapes - be it low or high profile, plus single or double sided RAM arrangements.

DFI Launches Ruggedized IP69K Rated Waterproof Industrial Computer ECX700-AL

DFI, the global provider of industrial computers, has introduced its ECX700-AL ruggedized x86 PC for outdoor edge computing applications. Its impeccable performance capabilities, compact size, and high durability make it the ideal solution for outdoor operations. The ECX700-AL is a rugged computer with a waterproof and dust-proof design to withstand harsh environments and any type of climate. Stable performance is ensured with its wide operating temperature of -40 to 70 degrees Celsius. It is also equipped with a smart vent that drains water automatically, preventing typical problems such as condensation within the system or excessive heat.

An external SIM slot provides convenience for users when changing SIM cards, and the high-gain antenna delivers a high-quality signal. Versatile I/O settings including a combo port that supports 2 CANs and 2 COMs as well as selective display ports (HDMI/VGA) help integrators meet demands for various applications.

Bloated Inventory and Manufacturers Sacrificing Pricing for Sales, Consumer DRAM Price Decline Expands to 13~18%, Says TrendForce

According to TrendForce investigations into the DRAM market, under pressure from ever-increasing output, Korean manufacturers have significantly increased their willingness to compromise on pricing in order to stimulate buying from distributors and customers, leading to a steady expansion of falling prices. In addition to Korean manufacturers enthusiastically slashing prices, low-priced chips from the spot market are also circulating in the market. Other suppliers have no choice but to follow suit and fervently reduce pricing for sales, rapidly exacerbating the 3Q consumer DRAM price drop from the original estimate of 8~13% to a quarterly decline of 13-18%.

Looking forward to Q4, it will be difficult for stocking momentum to recover before terminal inventories have been completely depleted. TrendForce expects the price of consumer DRAM to continue to fall until oversupply in the market is alleviated. Thus, consumer DRAM pricing will carry on moving lower by another 3~8% in Q4 and the possibility of sustained decline cannot be ruled out.

Pincered by Russian-Ukrainian War and Inflation, DRAM Price Drop Forecast to Continue in 2Q22 by 0-5%, Says TrendForce

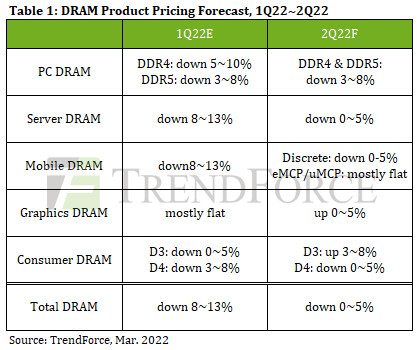
According to TrendForce forecasts, average overall DRAM pricing in 2Q22 will drop by approximately 0~5%, due to marginally higher buyer and seller inventories coupled with the demand for products such as PCs, laptops, and smart phones being influenced in the short-term by the Russian-Ukrainian war and high inflation weakening consumer purchasing power. At present, the only remaining source of demand is on the server side, so overall DRAM stocks will remain oversupplied in 2Q22.

In terms of PC DRAM, PC OEMs are adopting a conservative stocking strategy for orders in 2Q22 due to the Russian-Ukrainian war, which may continue affecting orders during peak season in 2H22, and revising 2022 shipment targets downwards. Additionally, the overall supply of bits is still growing, so the PC DRAM price slump in 2Q22 will further expand to 3~8% and may continue to deteriorate.

TrendForce: DDR3 Consumer DRAM Prices Expected to Rise by 0-5% in 2Q22 Due to Rapidly Shrinking Supply

Intel and AMD will be releasing new CPUs that support DDR5 DRAM solutions for PCs and servers this year. In response, the DRAM industry led by South Korean suppliers is developing solutions to complement the arrival of the new CPUs. In the midst of the gradual shift to DDR5, DRAM suppliers will also scale back the supply of DDR3 solutions, according to TrendForce's latest investigations. With Korean suppliers accelerating their withdrawal from DDR3 production, Taiwanese suppliers yet to kick off mass production using newly installed capacities, and Chinese suppliers falling short of their expected yield rate, the global supply of DDR3 solutions will undergo an impending decline. With respect to the demand side, however, not only has the supply of networking chips been ramping up, but material shortage issues are also gradually easing. As such, buyers are now procuring DDR3 solutions ahead of time, resulting in a tight supply and demand situation in the DDR3 market. TrendForce therefore expects DDR3 DRAM prices to recover from a bearish first quarter and undergo a 0-5% QoQ increase in 2Q22.
Return to Keyword Browsing
Nov 11th, 2026 03:13 CST change timezone

New Forum Posts

Popular Reviews

TPU on YouTube

Controversial News Posts